A qualified pension represents one of the most powerful retirement savings vehicles available to American workers today. These employer-sponsored retirement plans meet specific Internal Revenue Service requirements, offering significant tax advantages while helping individuals build wealth for their later years. Understanding the nuances of how these plans work, their regulatory framework, and their role in comprehensive retirement planning can make the difference between a comfortable retirement and financial uncertainty. Whether you're an employee evaluating benefit packages or someone approaching retirement with pension assets, grasping these fundamentals is essential for making informed decisions about your financial future.
What Defines a Qualified Pension Plan
A qualified pension plan is a retirement arrangement established by an employer that meets the requirements outlined in Section 401(a) of the Internal Revenue Code. This qualification status provides substantial benefits to both employers and employees, primarily through favorable tax treatment.
The core characteristics that distinguish qualified pension plans include:
- Employer contributions are tax-deductible as a business expense
- Employee contributions (if allowed) are made with pre-tax dollars
- Investment earnings grow tax-deferred until withdrawal
- Plans must meet strict nondiscrimination rules to prevent favoring highly compensated employees
- Assets are held in a trust separate from the employer's general assets
The qualification requirements established by the IRS ensure these plans serve their intended purpose of providing broad-based retirement security rather than becoming executive perks. This regulatory framework creates a level playing field while encouraging employers to offer meaningful retirement benefits.
Two Main Types of Qualified Pension Plans
The landscape of qualified pension arrangements falls into two primary categories, each with distinct features and risk allocations.
Defined Benefit Plans promise a specific monthly benefit at retirement, calculated using a formula that typically considers salary history and years of service. The employer bears the investment risk and must contribute enough to fund the promised benefits. These traditional pensions have become less common in the private sector but remain prevalent in government employment.
Defined Contribution Plans specify contribution amounts rather than benefit levels. The most familiar example is the 401(k) plan. In these arrangements, the employee often bears the investment risk, and the ultimate retirement benefit depends on contribution levels and investment performance over time.
| Feature | Defined Benefit | Defined Contribution |
|---|---|---|
| Benefit certainty | Fixed monthly payment | Depends on account balance |
| Investment risk | Employer assumes | Employee assumes |
| Portability | Limited (often annuity) | High (account can roll over) |
| Predictability | Very high | Variable |
| Administrative complexity | High | Moderate |
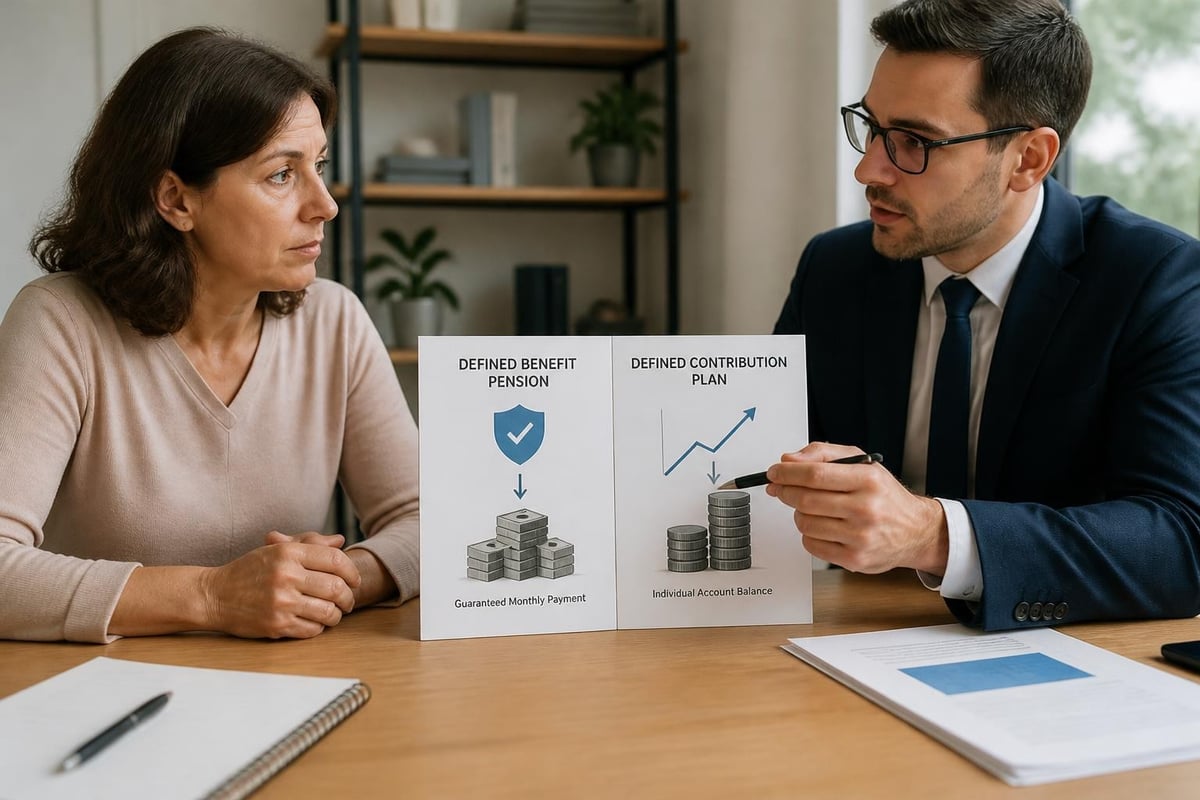
The shift from defined benefit to defined contribution plans has transformed the retirement landscape over recent decades. This evolution has placed greater responsibility on individuals to manage their own retirement savings and investment decisions.
Tax Advantages of Qualified Pension Arrangements
The qualified pension structure delivers powerful tax benefits that accelerate wealth accumulation for retirement. These advantages create a compelling reason for workers to maximize their participation when offered these benefits.
Current Year Tax Reductions
Contributions to a qualified pension plan typically reduce your taxable income in the year you make them. If you contribute $10,000 to your 401(k) and you're in the 24% tax bracket, you potentially save $2,400 in federal income tax that year. This immediate benefit makes contributions more affordable than many people realize.
Employer contributions to qualified pension plans also receive favorable treatment. Businesses can deduct these contributions as ordinary business expenses, creating an incentive to offer competitive retirement benefits. This tax dynamic has supported the widespread adoption of these plans across American workplaces.
Tax-Deferred Growth
Once inside a qualified pension plan, your investments grow without annual tax consequences. You don't pay taxes on dividends, interest, or capital gains while funds remain in the plan. This tax deferral compounds over decades, potentially adding hundreds of thousands of dollars to your retirement nest egg.
Consider two identical investments of $50,000 growing at 7% annually. In a taxable account (assuming 24% tax on all gains), you'd accumulate approximately $216,000 after 30 years. The same investment in a qualified pension plan would grow to roughly $380,000-a difference of $164,000 solely from tax-deferred compounding.
Distribution Tax Treatment
When you eventually take distributions from a qualified pension plan, they're generally taxed as ordinary income. The IRS Publication 575 provides comprehensive guidance on pension and annuity income taxation, including special rules for lump-sum distributions and required minimum distributions.
Many retirees find themselves in lower tax brackets during retirement than during their peak earning years. This bracket arbitrage-contributing when rates are high and withdrawing when rates are lower-adds another layer of tax efficiency to qualified pension strategies.
Contribution Limits and Nondiscrimination Rules
Qualified pension plans operate within carefully defined regulatory boundaries designed to ensure fairness and prevent abuse. Understanding these limits helps you optimize your retirement savings strategy.
Annual Contribution Caps
For 2026, defined contribution plans like 401(k)s have employee deferral limits of $23,500 for those under 50, and $31,000 for participants age 50 and older (including catch-up contributions). Total contributions from all sources (employee deferrals, employer match, profit sharing) cannot exceed $69,000, or $76,500 for those eligible for catch-up contributions.
Key contribution considerations include:
- Maximizing employer matching contributions first (free money)
- Understanding how bonuses and commissions affect percentage-based deferrals
- Coordinating multiple employer plans if you change jobs mid-year
- Utilizing catch-up contributions once you reach age 50
- Balancing qualified pension contributions with other savings goals
These limits adjust periodically for inflation, making it important to review your contribution strategy annually with a financial professional who can integrate these decisions into your broader financial picture.
Nondiscrimination Testing
Qualified pension plans must pass annual nondiscrimination tests ensuring benefits don't disproportionately favor highly compensated employees. These tests examine both contribution rates and benefit accruals across different employee groups.
If a plan fails these tests, corrective action is required. Common remedies include refunding excess contributions to highly paid workers or making additional contributions for non-highly compensated employees. Safe harbor plan designs can bypass some testing requirements by meeting specific contribution formulas.
Working with experienced retirement planning professionals helps ensure your qualified pension participation aligns with these rules while maximizing your personal benefit.
Vesting and Portability Considerations
Vesting determines when you gain ownership of employer contributions to your qualified pension plan. Understanding vesting schedules is crucial for career planning and job transition decisions.
Vesting Schedules Explained
Cliff vesting grants you 100% ownership after a specified period (often three years). Before reaching that cliff, you have zero ownership of employer contributions. One day before the vesting date, you own nothing; one day after, you own everything.
Graded vesting transfers ownership gradually. A common schedule might grant 20% ownership after two years, then 20% additional ownership each subsequent year until you reach 100% at six years. Your own contributions are always immediately 100% vested.
| Years of Service | Cliff Vesting | Graded Vesting |
|---|---|---|
| 0-2 years | 0% | 0% |
| 3 years | 100% | 40% |
| 4 years | 100% | 60% |
| 5 years | 100% | 80% |
| 6 years | 100% | 100% |
Portability and Rollovers
When you leave an employer with a qualified pension plan, you typically have several options for your vested balance. You might leave the funds in your former employer's plan, roll them to your new employer's plan, roll them to an Individual Retirement Account (IRA), or take a taxable distribution (generally not recommended before retirement age).
Direct rollovers-where funds transfer directly between qualified accounts-avoid mandatory withholding and potential tax consequences. Indirect rollovers, where you receive a check, trigger 20% mandatory withholding and must be completed within 60 days to avoid taxes and potential penalties.
Strategic rollover decisions depend on factors including investment options, fee structures, creditor protection rules, and your overall retirement timeline. Professional guidance from a fiduciary advisor can help you navigate these transitions while preserving your retirement assets.
Distribution Rules and Required Minimum Withdrawals
Qualified pension plans include specific rules governing when and how you can access your money. These regulations balance retirement security objectives with government revenue needs.
Early Distribution Penalties
Generally, distributions before age 59½ incur a 10% early withdrawal penalty in addition to ordinary income taxes. However, numerous exceptions exist, including:
- Separation from service after age 55 (age 50 for public safety employees)
- Disability
- Substantially equal periodic payments (SEPP)
- Qualified domestic relations orders (divorce settlements)
- Medical expenses exceeding 7.5% of adjusted gross income
- First-time home purchases (up to $10,000, IRA only)
These exceptions have specific requirements and limitations. Misapplying them can result in unexpected tax bills and penalties.
Required Minimum Distributions
Once you reach age 73 (for those born in 1951 or later), you must begin taking required minimum distributions (RMDs) from most qualified pension plans. The annual RMD amount is calculated by dividing your account balance by a life expectancy factor published by the IRS.
RMD planning considerations include:
- Timing your first distribution (can delay until April 1 of the year after you turn 73)
- Coordinating distributions across multiple retirement accounts
- Understanding RMD aggregation rules (which accounts can be grouped)
- Planning for the tax impact of large required distributions
- Considering qualified charitable distributions as a tax-efficient strategy
Failing to take your full RMD results in a 25% excise tax on the shortfall amount-one of the steepest penalties in the tax code. Careful planning and calendar management prevent these costly mistakes.
Plan Termination and Benefit Protections
Understanding what happens if a qualified pension plan terminates provides important context for evaluating these benefits and planning appropriately.
Standard Terminations
In a standard termination of a defined benefit plan, the plan has sufficient assets to pay all promised benefits. The plan administrator typically purchases annuities from insurance companies to cover benefit obligations or offers lump-sum distributions to participants. The PBGC termination process outlines the specific steps and timeline required.
For defined contribution plans, termination typically involves distributing account balances to participants or rolling them into successor plans. Since these plans don't promise specific benefit levels, termination is more straightforward.
Distress and Involuntary Terminations
When a company faces financial distress and cannot fully fund its defined benefit pension obligations, the Pension Benefit Guaranty Corporation (PBGC) may become involved. The PBGC is a federal agency that insures private-sector defined benefit plans.
The PBGC protection limits vary based on your age and benefit commencement date, but they may not cover the full promised benefit for higher earners. Understanding these protections helps you assess the security of your pension benefits and whether additional retirement savings are prudent.
Integration with Comprehensive Retirement Planning
A qualified pension plan is rarely your only retirement asset. Effective retirement planning integrates these benefits with Social Security, personal savings, real estate, and other income sources.
Coordinating Multiple Income Streams
Strategic sequencing determines which accounts you tap first in retirement. Common approaches include:
- Spending taxable accounts first while allowing tax-deferred accounts to continue growing
- Managing distributions to stay within favorable tax brackets
- Delaying Social Security to increase lifetime benefits while living on qualified pension distributions
- Using Roth conversions during lower-income years to create future tax-free income
The optimal strategy depends on your specific tax situation, longevity expectations, estate planning goals, and spending needs. Generic rules of thumb often miss important optimization opportunities worth tens of thousands of dollars over a retirement spanning several decades.
Estate Planning Considerations
Qualified pension plans pass to designated beneficiaries outside of probate, making beneficiary designation forms critical estate planning documents. Review these designations after major life events like marriage, divorce, or the birth of children.
The SECURE Act of 2019 eliminated the "stretch IRA" for most non-spouse beneficiaries, requiring inherited qualified pension accounts to be fully distributed within 10 years. This change has significant tax implications for beneficiaries and may affect your legacy planning strategies. Coordination with estate planning services ensures your retirement assets transfer efficiently.
Tax Strategy Across Decades
Effective qualified pension planning looks decades ahead, considering how today's decisions affect tomorrow's tax bills. Pre-retirement Roth conversions, charitable contribution strategies using qualified charitable distributions, and careful Social Security timing all interact with your qualified pension distributions.
Year-to-year tax planning should consider:
- Projecting income needs and sources for the next 5-10 years
- Identifying opportunities to accelerate or defer income
- Evaluating the impact of state taxes (which vary dramatically)
- Understanding how investment decisions within the plan affect long-term growth
- Recognizing how required minimum distributions will affect future tax brackets
Plan Selection and Optimization for Employees
When you have choices about qualified pension participation, making informed decisions can significantly impact your retirement readiness.
Evaluating Employer Plan Features
Not all qualified pension plans offer the same features or investment quality. Important factors to assess include:
- Employer matching formulas and vesting schedules
- Investment menu quality, diversity, and expense ratios
- Availability of Roth options for after-tax contributions
- Loan provisions (whether you can borrow against your balance)
- In-service distribution rules
- Auto-enrollment and auto-escalation features
- Access to professional advice or managed account services
Plans with low-cost index funds, generous matching, and immediate vesting provide substantially more value than plans with expensive actively managed funds, minimal matching, and lengthy vesting periods.
Contribution Rate Decisions
Determining how much to contribute involves balancing multiple objectives. At minimum, contribute enough to capture the full employer match-it's the highest guaranteed return available. Beyond that, consider your emergency fund status, high-interest debt, and other financial priorities.
A systematic approach might follow this sequence:
- Contribute to capture full employer match (immediate 50%-100% return)
- Pay off high-interest debt (credit cards, certain personal loans)
- Build 3-6 months of expenses in emergency savings
- Increase qualified pension contributions toward the annual limit
- Fund other goals (education savings, taxable investment accounts, real estate)
This framework provides a starting point, but personal circumstances vary. Someone with a pension may prioritize differently than someone whose qualified pension plan represents their sole retirement savings vehicle.
Roth vs. Traditional Contributions
Many qualified pension plans now offer Roth options, allowing you to make after-tax contributions in exchange for tax-free qualified distributions in retirement. This choice depends on your current versus expected future tax rates.
Roth contributions typically make more sense when:
- You're early in your career with relatively lower current income
- You expect substantially higher income in retirement
- Tax rates seem likely to increase in the future
- You want tax diversification in retirement
- You're already maxing traditional contributions and want to save more
Traditional pre-tax contributions remain valuable for those in peak earning years who expect lower retirement income or who need the current tax deduction to make contributions affordable.
Self-Employed and Small Business Qualified Pension Options
Business owners and self-employed professionals can establish qualified pension plans tailored to their specific situations, often with higher contribution limits than typical employee plans.
SEP-IRA and SIMPLE IRA Plans
Simplified Employee Pension (SEP) IRAs allow employers to contribute up to 25% of compensation (or 20% of net self-employment income), with a maximum contribution of $69,000 in 2026. These plans feature minimal administration and no annual filing requirements for businesses.
SIMPLE IRAs suit smaller businesses with up to 100 employees. They allow employee deferrals of $16,000 in 2026 ($19,500 for those 50 and older), with mandatory employer contributions through either dollar-for-dollar matching up to 3% of compensation or a 2% non-elective contribution for all eligible employees.
Solo 401(k) Plans
Self-employed individuals without employees (other than a spouse) can establish solo 401(k) plans combining employee deferrals and employer profit-sharing contributions. This structure potentially allows total contributions of $69,000 annually ($76,500 with catch-up), significantly higher than most other options.
Solo 401(k) plans also offer loan provisions, Roth options, and the ability to make large catch-up contributions for business owners who got a late start on retirement savings. Working with financial advisors experienced with business owner planning helps structure these plans for maximum benefit while ensuring ongoing compliance.
Defined Benefit Plans for High Earners
Business owners with substantial income and relatively few employees might consider cash balance or traditional defined benefit plans. These qualified pension arrangements can support annual contributions exceeding $200,000 for older, high-earning business owners-far beyond defined contribution limits.
The trade-off involves higher administrative complexity, mandatory annual funding requirements, and PBGC premiums. However, for the right situation, these plans provide unmatched retirement savings acceleration and current-year tax deductions.
Common Mistakes to Avoid
Even sophisticated professionals make errors with qualified pension plans that cost them thousands of dollars in lost growth or unnecessary taxes.
Leaving Employer Matches Unclaimed
Approximately one-third of employees fail to contribute enough to receive their full employer match. This represents leaving guaranteed returns on the table-essentially turning down a portion of your compensation package.
Poor Investment Selection
Many participants default to overly conservative options like stable value funds or money market investments, significantly reducing long-term growth potential. Others chase performance or fail to diversify properly. Your investment horizon, risk tolerance, and overall financial picture should guide qualified pension investment decisions.
Forgetting About Old Accounts
The average worker changes jobs 12 times during their career. Each transition creates an opportunity to lose track of qualified pension accounts. Consolidating old accounts through rollovers simplifies management and often reduces fees while ensuring nothing gets forgotten.
Taking Loans Inappropriately
While many qualified pension plans allow loans, borrowing from retirement accounts has hidden costs. You lose investment growth on borrowed amounts, you repay loans with after-tax dollars that will be taxed again upon distribution, and if you leave your employer before repayment, the outstanding balance becomes a taxable distribution.
Neglecting Beneficiary Designations
Beneficiary forms control qualified pension asset distribution regardless of what your will or trust says. Outdated beneficiary designations-naming an ex-spouse or deceased parent-create significant problems for your heirs. Review these designations annually and after every major life event.
Qualified pension plans remain cornerstone elements of retirement security for millions of Americans, offering unmatched tax advantages and disciplined savings frameworks that build wealth over time. Whether you participate in an employer-sponsored plan or establish one for your own business, understanding the rules, maximizing the benefits, and integrating these assets into your comprehensive financial strategy determines whether you achieve your retirement goals. Brookwood Investment Group provides personalized, fiduciary guidance to help you optimize qualified pension decisions within your broader retirement plan, investment strategy, and tax picture-ensuring every dollar works efficiently toward your unique vision for financial independence.
