Retirement planning extends far beyond traditional 401(k) accounts and IRAs. For high-earning executives, business owners, and key employees, a non qualified pension plan offers unique opportunities to defer compensation and build retirement savings beyond the limits imposed on qualified plans. These arrangements provide flexibility in design and eligibility but come with distinct tax treatment, regulatory requirements, and risk considerations. Understanding how these plans work, their compliance obligations under Section 409A, and their strategic role in comprehensive financial planning is essential for anyone considering or participating in such arrangements.
What Defines a Non Qualified Pension Plan
A non qualified pension plan is a deferred compensation arrangement that does not meet the requirements of Section 401(a) of the Internal Revenue Code. Unlike qualified plans, these arrangements are not subject to many ERISA protections, do not receive the same tax advantages for employers, and expose participants to employer credit risk.
The fundamental distinction lies in regulatory treatment. Qualified plans must satisfy nondiscrimination rules, coverage requirements, and contribution limits established by the IRS. A non qualified pension bypasses these restrictions, allowing employers to offer selective benefits to executives and highly compensated employees without triggering the same compliance burdens.
Key Structural Characteristics
These plans typically take several forms, each with specific features:
- Supplemental Executive Retirement Plans (SERPs) that provide additional retirement benefits beyond qualified plan limits
- Deferred compensation agreements allowing employees to defer salary, bonuses, or incentive payments
- Excess benefit plans that restore benefits lost due to qualified plan compensation caps
- Top-hat plans covering a select group of management or highly compensated employees
Most arrangements are unfunded, meaning the employer maintains a contractual promise to pay future benefits rather than segregating assets in a trust. This structure creates tax advantages but increases participant risk.
Tax Treatment and Timing Considerations
The taxation of a non qualified pension differs significantly from qualified retirement accounts. Participants generally do not pay income tax when compensation is deferred, provided the arrangement complies with Section 409A regulations. Instead, taxes are deferred until actual or constructive receipt occurs.
When distributions begin, the entire amount is taxed as ordinary income. Unlike Roth accounts, there is no tax-free growth component. The employer receives a tax deduction when amounts are included in the participant's income, creating a matching of deduction and inclusion.
Section 409A Compliance Requirements
Congress enacted Section 409A in 2004 to regulate the timing of deferrals and distributions. Violations trigger immediate income inclusion, a 20% additional tax, and potential interest penalties. The IRS guidance on nonqualified deferred compensation outlines the specific requirements.
Permissible distribution events under Section 409A include:
- Separation from service
- Disability
- Death
- A specified time or fixed schedule
- Change in ownership or control
- Unforeseeable emergency
Elections to defer compensation must generally be made before the calendar year in which services are performed. For performance-based compensation, elections may be made up to six months before the end of the performance period, provided the outcome remains substantially uncertain.
| Compliance Element | Requirement | Penalty for Violation |
|---|---|---|
| Initial deferral election | Before year of service | Immediate inclusion + 20% tax |
| Distribution timing | Limited to six events | Immediate inclusion + 20% tax |
| Subsequent changes | Delayed 5 years, 12-month advance notice | Immediate inclusion + 20% tax |
| Funding restrictions | Substantial risk of forfeiture or unfunded | Immediate inclusion + 20% tax |
Working with experienced professionals who understand fiduciary planning is essential to navigate these complex rules and avoid costly mistakes.
Advantages for High Earners and Executives
For individuals who maximize contributions to qualified plans, a non qualified pension provides the primary vehicle for additional tax-deferred retirement savings. The 2026 contribution limit for 401(k) plans is $23,500 (with $7,500 in catch-up contributions for those 50 and older), which represents a small fraction of total compensation for senior executives.
Strategic benefits include:
- Unlimited deferral amounts beyond qualified plan caps
- Flexible distribution scheduling aligned with retirement income needs
- Customized benefit formulas that reward tenure, performance, or achievement
- Estate planning coordination through beneficiary designations and continuation options
These arrangements also serve retention purposes. Employers structure vesting schedules and forfeiture provisions that encourage key employees to remain with the organization through critical periods.
The ability to defer compensation into lower-tax years creates meaningful tax arbitrage. An executive earning $500,000 annually who defers $150,000 avoids immediate taxation at potentially 37% federal rates, plus state income taxes. If distributions occur in retirement when income is lower, the tax savings can be substantial.
Employer Considerations and Plan Design
Organizations implement nonqualified plans for talent management, retention, and competitive positioning. However, these arrangements create financial statement obligations, administrative complexity, and potential cash flow commitments.
Accounting and Financial Impact
Under ASC 718 and related accounting standards, employers must recognize the liability associated with deferred compensation promises. The present value of future obligations appears on the balance sheet, creating earnings volatility as assumptions change. Resources on valuation and accounting treatment help organizations model these impacts.
Employers often purchase corporate-owned life insurance (COLI) to informally fund future obligations. While these assets do not secure participant benefits-maintaining unfunded status for tax purposes-they provide cash value growth to offset future payment requirements.
Design decisions include:
- Benefit calculation formulas (percentage of final average compensation, flat dollar amounts, or contribution-based)
- Vesting schedules and forfeiture conditions
- Investment crediting methods (fixed rates, equity indices, or hypothetical investments)
- Distribution forms (lump sum, installments, or life annuities)
- Change in control protections or acceleration provisions
The IRS employer guidance addresses withholding, reporting, and payroll tax treatment when designing these programs.
Risk Factors and Protection Limitations
Unlike qualified plans protected by ERISA and insured by the Pension Benefit Guaranty Corporation, a non qualified pension exposes participants to employer insolvency risk. Benefits represent unsecured general creditor claims, ranking alongside other corporate obligations in bankruptcy.
This fundamental risk distinguishes nonqualified arrangements from protected retirement accounts. Even substantial account balances can be lost if the employer faces financial distress. Participants must evaluate employer creditworthiness as part of their decision to defer compensation.
Mitigation Strategies
While complete protection is not possible without triggering immediate taxation, participants can take several steps:
- Diversify retirement assets across qualified plans, IRAs, and taxable accounts rather than concentrating in nonqualified deferrals
- Monitor employer financial health through public filings, credit ratings, and industry conditions
- Limit deferral percentages to balance tax benefits against concentration risk
- Accelerate distributions when permitted if employer circumstances deteriorate
Some employers establish rabbi trusts-irrevocable trusts that hold assets to pay future benefits while remaining subject to creditor claims. These structures provide protection against employer unwillingness to pay (change of heart) but not inability to pay (insolvency).
Organizations offering retirement planning services help clients evaluate these risk trade-offs within their overall financial strategy.
Integration with Comprehensive Financial Planning
A non qualified pension should not exist in isolation but rather as one component of a coordinated retirement and tax strategy. Integration requires considering multiple planning dimensions simultaneously.
Tax planning coordination involves projecting future income across sources, modeling marginal rates in different years, and timing distributions to minimize lifetime tax burdens. Deferring compensation into years with lower rates, whether due to retirement or geographic relocation, creates value beyond investment returns.
Estate planning considerations include beneficiary designations, estate tax exposure for large balances, and the income tax treatment of benefits inherited by heirs. Unlike Roth IRAs, nonqualified plan benefits do not receive stepped-up basis and create income in respect of a decedent (IRD), triggering both estate and income taxes.
Investment strategy must account for the crediting method used in the plan. If benefits are based on hypothetical investment elections mirroring mutual funds or indices, participants effectively have asset allocation control. Understanding how these phantom investments interact with actual portfolio holdings prevents unintended concentration or asset class misalignment.
| Planning Area | Integration Consideration | Professional Guidance Value |
|---|---|---|
| Tax optimization | Deferral timing, distribution scheduling, rate arbitrage | Model scenarios across income projections |
| Investment allocation | Hypothetical vs. actual holdings, total portfolio view | Prevent duplicated exposures |
| Estate planning | Beneficiary structure, IRD implications, liquidity needs | Coordinate with trust planning |
| Risk management | Employer credit exposure, diversification across accounts | Evaluate concentration risk |
| Cash flow planning | Distribution election, spending needs, other income sources | Align with retirement planning |
Compliance, Corrections, and Operational Challenges
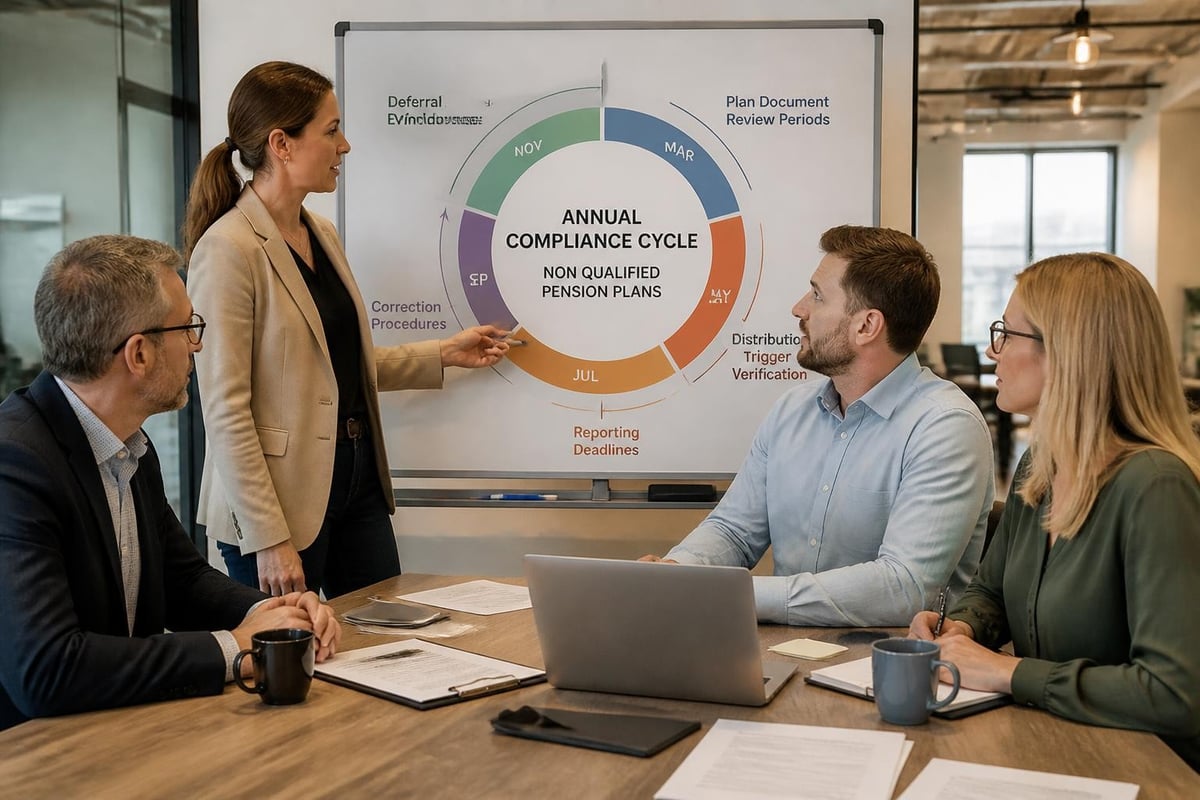
Maintaining Section 409A compliance requires ongoing attention to plan administration, documentation, and operational practices. Common pitfalls include impermissible acceleration of payments, untimely deferral elections, and constructive receipt issues.
The practitioner guidance on 409A compliance addresses correction methods for operational failures. The IRS provides limited correction opportunities through operational compliance programs, but corrections must occur before examination and may require participant income inclusion for prior years.
Administrative best practices include:
- Annual review of plan documents for consistency with current law
- Documented procedures for deferral elections and distribution requests
- Coordination between HR, payroll, and benefits teams on timing requirements
- Regular training for administrators on Section 409A rules
- Engagement of specialized counsel for plan amendments or design changes
Employers must also address reporting and fringe benefit considerations when administering these arrangements, ensuring proper Form W-2 and 1099 reporting.
Distribution Planning and Timing Strategies
When and how to receive nonqualified plan distributions represents a critical planning decision with lasting tax and financial implications. Elections made years before retirement become binding, requiring careful forecasting of future circumstances.
Many plans require participants to elect distribution timing and form when initially deferring compensation. Changing these elections later triggers the Section 409A requirement that changes be made at least 12 months before the scheduled payment date and delay distributions by at least five years.
Strategic Distribution Approaches
Lump sum distributions provide immediate access to capital and eliminate future employer credit risk. However, they can create significant tax bunching, potentially pushing income into higher brackets or triggering additional Medicare premiums through the Income-Related Monthly Adjustment Amount (IRMAA).
Installment payments spread tax recognition across multiple years, smoothing marginal rates and potentially reducing total lifetime taxes. A typical structure might pay benefits over 10 or 15 annual installments beginning at retirement.
Annuity forms provide guaranteed income streams but sacrifice flexibility and liquidity. These structures work well for participants seeking pension-like income certainty.
Optimal distribution design considers:
- Projected retirement income from Social Security, pensions, and investment accounts
- Anticipated tax bracket changes due to Required Minimum Distributions from IRAs
- Major planned expenditures (real estate purchases, travel, family support)
- Health status and longevity expectations
- Estate planning objectives and intended beneficiaries
Professionals offering customized planning services model these scenarios to identify the most tax-efficient distribution structure for individual circumstances.
Evaluating Whether Participation Makes Sense
Not every eligible employee should maximize nonqualified plan deferrals. The decision requires weighing tax benefits against risks, evaluating alternative savings vehicles, and considering personal financial circumstances.
Ideal candidates typically have:
- Maximized contributions to qualified retirement plans and IRAs
- Strong employer financial health and stability
- High current marginal tax rates with expected lower rates in retirement
- Sufficient liquidity in taxable accounts for near-term needs
- Long time horizons before requiring access to deferred amounts
Less suitable situations include:
- Concerns about employer creditworthiness or industry stability
- Anticipated need for capital before distribution eligibility
- Equivalent or higher expected tax rates in retirement
- Preference for Roth-style tax-free growth in qualified accounts
- Limited diversification in other retirement savings
The concentration of retirement assets in a single employer creates both investment and credit risk. Particularly for executives whose human capital is already tied to employer success, additional concentration through nonqualified deferrals compounds this exposure.
Alternative strategies might include maximizing after-tax 401(k) contributions with in-plan Roth conversions, funding backdoor Roth IRAs, establishing donor-advised funds for charitable planning, or increasing taxable investment account contributions. Each approach creates different tax, liquidity, and flexibility profiles.
Role of Professional Guidance
The complexity of a non qualified pension, combined with significant tax and financial consequences, makes professional guidance valuable for both participants and plan sponsors. Expertise spans multiple disciplines including tax law, retirement planning, investment management, and estate planning.
Participants benefit from professionals who can:
- Model tax impacts of different deferral and distribution scenarios
- Integrate nonqualified plan decisions with overall financial strategy planning
- Monitor employer financial health and recommend risk mitigation
- Coordinate benefit timing with Social Security claiming, Roth conversions, and other retirement decisions
- Update plans as tax laws, personal circumstances, or employer conditions change
Employers need advisors who understand plan design, Section 409A compliance, accounting implications, and competitive benchmarking. The intersection of legal, tax, and human resources considerations requires coordinated expertise.
Virtual-first advisory models have made specialized guidance more accessible. Rather than being limited to local professionals, participants can work with experts who focus specifically on executive compensation and nonqualified plan strategies regardless of geographic location.
A non qualified pension can be a powerful tool for executives and high earners seeking to defer taxation and build retirement savings beyond qualified plan limits, but success requires understanding the compliance requirements, risk factors, and strategic integration with comprehensive financial planning. Brookwood Investment Group offers personalized guidance on retirement planning, tax strategies, and investment management tailored to your unique circumstances and goals-schedule a conversation to explore how nonqualified pension planning fits within your overall financial strategy.
