Understanding the maximum allowable contribution to your Individual Retirement Account is essential for building a sustainable retirement strategy. The max IRA deposit can change annually based on inflation adjustments, and knowing these limits helps you maximize tax advantages while staying compliant with IRS regulations. Whether you're contributing to a Traditional IRA, Roth IRA, or both, navigating contribution caps, income phase-outs, and catch-up provisions requires careful planning to make the most of your retirement savings opportunities in 2026.
Annual Contribution Limits for 2026
The IRS sets annual contribution limits for IRAs based on cost-of-living adjustments. For 2026, the standard max IRA deposit remains consistent with recent adjustments designed to help Americans build retirement security.
For individuals under age 50, the maximum contribution across all Traditional and Roth IRAs combined is $7,000 for the 2026 tax year. This represents the total amount you can deposit, not a per-account limit.
Key contribution facts:
- The $7,000 limit applies to combined Traditional and Roth IRA contributions
- You cannot exceed this amount even if you have multiple IRA accounts
- Contributions can be made until the tax filing deadline (typically April 15, 2027, for the 2026 tax year)
- Excess contributions face a 6% penalty tax each year they remain in the account
Catch-Up Contributions for Age 50 and Older
Workers who have reached age 50 by December 31, 2026, qualify for additional catch-up contributions. This provision recognizes that older workers often need to accelerate retirement savings as they approach their target retirement date.
The catch-up contribution amount for 2026 is an additional $1,000, bringing the total max IRA deposit to $8,000 for eligible individuals. This catch-up provision applies whether you contribute to a Traditional IRA, Roth IRA, or split contributions between both account types.
Recent regulatory changes under SECURE 2.0 have introduced new requirements for certain high-income earners regarding how catch-up contributions must be treated, though these provisions primarily affect employer-sponsored plans rather than IRAs.
Income Limits and Phase-Out Ranges
While Traditional IRA contribution limits are straightforward, the max IRA deposit for Roth IRAs depends on your modified adjusted gross income (MAGI) and tax filing status. These income phase-outs determine whether you can contribute the full amount, a reduced amount, or nothing at all to a Roth IRA.
Roth IRA Income Phase-Outs for 2026
Roth IRA income limits create a tiered system where contribution eligibility gradually decreases as income rises. Understanding these thresholds helps you plan contributions accurately and explore alternative strategies when direct Roth contributions aren't available.
| Filing Status | Phase-Out Begins | Phase-Out Complete | Max Contribution at Lower Limit |
|---|---|---|---|
| Single/Head of Household | $150,000 | $165,000 | $7,000 ($8,000 if 50+) |
| Married Filing Jointly | $236,000 | $246,000 | $7,000 ($8,000 if 50+) |
| Married Filing Separately | $0 | $10,000 | Reduced amount only |
When your income falls within the phase-out range, you must calculate your reduced contribution limit using the IRS worksheet provided in Publication 590-A. This calculation determines your exact max IRA deposit based on your precise income level.
Deductibility of Traditional IRA Contributions
Traditional IRA contributions may be tax-deductible depending on your income and whether you or your spouse participate in an employer-sponsored retirement plan. The max IRA deposit amount doesn't change based on deductibility, but the tax benefit you receive does.
Deduction phase-out ranges for 2026:
- Single filers covered by workplace plan: $77,000–$87,000
- Married filing jointly (contributor covered): $123,000–$143,000
- Married filing jointly (spouse covered, contributor not): $230,000–$240,000
- Married filing separately: $0–$10,000
Even when contributions aren't deductible, making them can still make sense for diversifying your tax treatment in retirement. Non-deductible contributions require careful recordkeeping using Form 8606 to track your basis and avoid double taxation upon withdrawal.
Strategic Considerations for Maximizing Contributions
Reaching your max IRA deposit each year represents a foundational retirement planning strategy, but the mechanics of when and how you contribute can significantly impact your long-term outcomes.
Timing Your Contributions
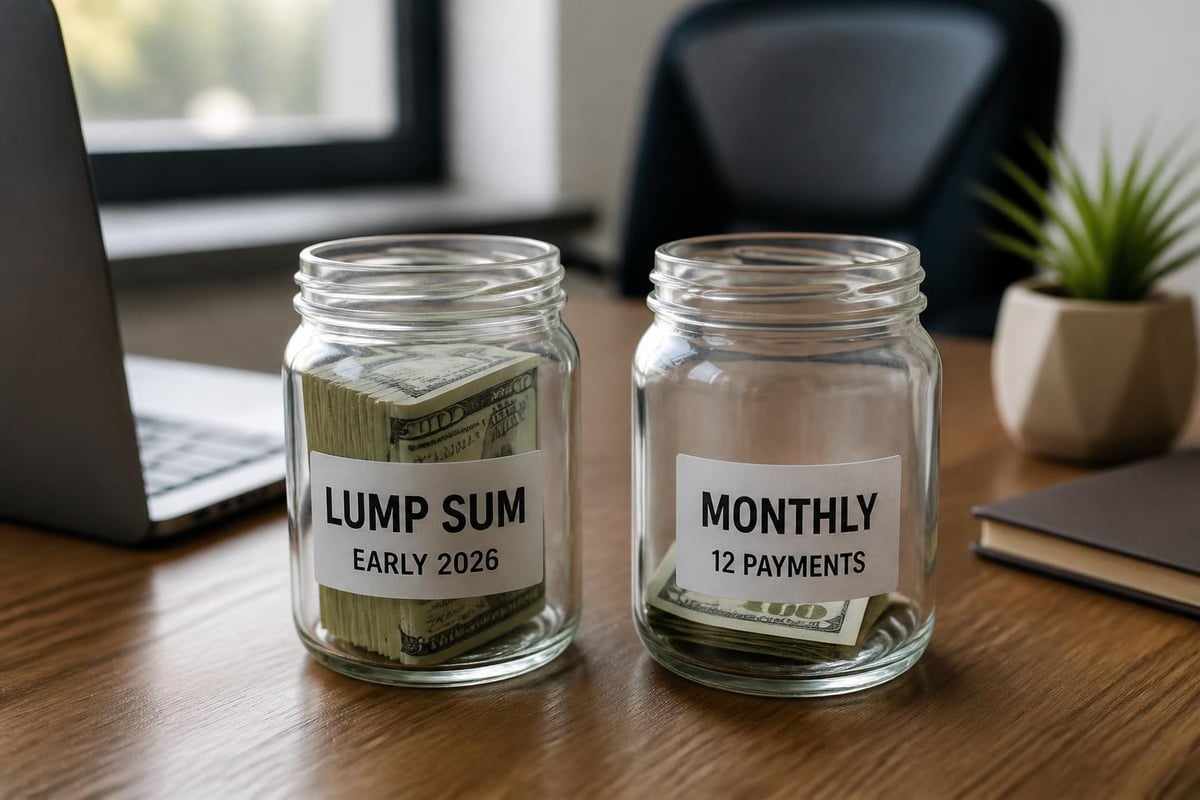
You have flexibility in how you fund your IRA throughout the year. Some investors prefer to make a lump-sum contribution at the beginning of the year to maximize time in the market, while others dollar-cost average by spreading contributions across twelve months.
Benefits of early contributions:
- Longer potential growth period
- Immediate tax deduction for Traditional IRA (if eligible)
- Psychological satisfaction of completing the task early
Advantages of systematic contributions:
- Reduces timing risk through dollar-cost averaging
- Easier to budget monthly amounts
- Allows for mid-year income adjustments if phase-outs become relevant
Neither approach is inherently superior, and the choice often depends on cash flow patterns, risk tolerance, and personal preferences. Working with a fiduciary advisor can help you determine which timing strategy aligns with your broader financial planning objectives.
Spousal IRA Contributions
Married couples where one spouse has little or no earned income can still maximize retirement savings through spousal IRA contributions. This provision allows the working spouse to contribute up to the max IRA deposit for both themselves and their non-working spouse, effectively doubling the household's annual IRA savings.
For 2026, a working spouse can contribute up to $7,000 ($8,000 if age 50+) to their own IRA and an additional $7,000 ($8,000 if age 50+) to a spousal IRA, for a combined total of $14,000 or $16,000 depending on age. The only requirement is that the working spouse must have earned income at least equal to the combined contributions.
Contribution Deadlines and Correction Procedures
Understanding when you can make contributions and how to fix errors helps you avoid penalties and maximize the max IRA deposit each year without complications.
Filing Deadline Extension
Unlike employer-sponsored plan contributions that typically must be made by December 31, IRA contributions can be made up until your tax filing deadline. For most taxpayers, this means you have until April 15, 2027, to make 2026 IRA contributions.
This extended deadline provides strategic flexibility. You can wait until you prepare your taxes to determine whether a Traditional or Roth contribution (or a mix) makes the most sense based on your actual income for the year.
- Determine your exact MAGI from your completed tax return
- Calculate your maximum allowable Roth IRA contribution based on phase-outs
- Decide the optimal split between Traditional and Roth contributions
- Make your contribution before the filing deadline
- Properly designate the tax year when making the contribution
Handling Excess Contributions
Contributing more than the max IRA deposit triggers a 6% excise tax on the excess amount for each year it remains in the account. Fortunately, the IRS provides clear guidance on correcting these errors.
Options for correcting excess contributions:
- Withdraw the excess amount and any earnings attributable to it before your tax filing deadline
- Recharacterize the contribution to a different IRA type if eligible
- Apply the excess to the following year's contribution limit
- Carry forward and absorb through future years when you contribute below the limit
The most common correction method involves withdrawing the excess contribution plus earnings before the tax deadline. Your IRA custodian can calculate the earnings attributable to the excess and process the corrective distribution.
Coordinating IRA Contributions with Other Retirement Accounts
The max IRA deposit operates independently from contribution limits for employer-sponsored plans like 401(k)s, 403(b)s, or 457 plans. This separation allows you to maximize contributions across multiple account types simultaneously.
Layering Multiple Retirement Accounts
High earners who max out their workplace retirement plans can still contribute the full max IRA deposit to boost their retirement savings, subject to income phase-outs for Roth IRAs and deductibility limits for Traditional IRAs.
| Account Type | 2026 Contribution Limit | Catch-Up (50+) | Income Restrictions |
|---|---|---|---|
| Traditional/Roth IRA | $7,000 | $1,000 | Yes (Roth only for contributions; both for deductibility) |
| 401(k)/403(b) | $23,000 | $7,500 | No (for contributions) |
| SIMPLE IRA | $16,000 | $3,500 | No |
| SEP IRA | Lesser of 25% compensation or $69,000 | None | No |
This table illustrates how different retirement vehicles stack, allowing sophisticated savers to potentially contribute over $100,000 annually across various accounts. Understanding how pension lump sum rollovers interact with ongoing contribution strategies adds another layer of complexity that benefits from professional guidance.
Backdoor Roth Strategies
High-income earners who exceed Roth IRA phase-out limits can still access Roth benefits through a backdoor Roth conversion strategy. This involves making a non-deductible Traditional IRA contribution up to the max IRA deposit, then converting it to a Roth IRA.
The SECURE 2.0 Act introduced several changes to retirement account rules, though it preserved the ability to perform Roth conversions. When executing a backdoor Roth strategy, careful attention to the pro-rata rule is essential if you have existing Traditional IRA balances with pre-tax dollars.
Tax Reporting and Recordkeeping Requirements
Properly documenting your IRA contributions protects you during tax season and ensures you can accurately track your basis for future withdrawals. The tax treatment of retirement accounts requires meticulous recordkeeping to avoid complications.
Form 5498 and Form 8606
Your IRA custodian will issue Form 5498 by May 31 following the contribution year, documenting all contributions made for that tax year. This form serves as your official record of having made the max IRA deposit and is used by the IRS to verify contribution compliance.
When you make non-deductible Traditional IRA contributions, you must file Form 8606 with your tax return. This form tracks your basis in Traditional IRAs, which becomes crucial when taking distributions to determine the taxable portion.
Critical recordkeeping documents:
- Annual Form 5498 from each IRA custodian
- Form 8606 for each year with non-deductible contributions
- Records of Roth conversions and recharacterizations
- Documentation of excess contribution corrections
- Beneficiary designation forms
Many taxpayers underestimate the importance of Form 8606, only to face challenges decades later when taking distributions. Maintaining complete records from the year you first make non-deductible contributions through your final distribution helps ensure accurate tax reporting.
Special Situations and Considerations
Certain circumstances create unique planning opportunities or restrictions around the max IRA deposit that merit specific attention.
Self-Employed Individuals
Self-employed workers can contribute to both a Traditional or Roth IRA and a SEP IRA or Solo 401(k) in the same year. The max IRA deposit limits apply separately from self-employed retirement plan contributions, though careful coordination ensures you maximize total retirement savings while managing tax obligations effectively.
A self-employed consultant earning $150,000 in 2026 could potentially contribute $7,000 to a Roth IRA (if MAGI permits) plus approximately $37,500 to a SEP IRA (25% of net self-employment income after the self-employment tax deduction), creating substantial tax-advantaged retirement savings.
Military Personnel and Combat Pay
Service members receiving tax-free combat pay have a unique advantage. While combat pay doesn't count as income for tax purposes, it does count as compensation for IRA contribution purposes. This allows military personnel to make the max IRA deposit while potentially owing little or no federal income tax, creating powerful Roth IRA opportunities.
Required Minimum Distributions and Contributions
Under current law, you can continue making IRA contributions at any age as long as you have earned income. The SECURE Act eliminated the age cap on Traditional IRA contributions, aligning it with Roth IRAs that never had an age restriction.
However, once you reach age 73 (for those turning 72 in 2023 or later), you must begin taking Required Minimum Distributions from Traditional IRAs. You can still make the max IRA deposit even while taking RMDs, though the strategies become more complex and often benefit from professional retirement planning guidance.
Employer-Sponsored IRA Programs
Some small businesses offer SIMPLE IRAs or SEP IRAs as their primary retirement benefit. Understanding how these relate to the max IRA deposit for Traditional and Roth IRAs helps employees optimize their overall retirement strategy.
SIMPLE IRA Interaction
SIMPLE IRA contributions count separately from Traditional and Roth IRA limits. An employee can contribute up to $16,000 to a SIMPLE IRA in 2026 (plus $3,500 catch-up if age 50+) and still make the full max IRA deposit of $7,000 ($8,000 with catch-up) to a Traditional or Roth IRA.
However, SIMPLE IRA participation may affect the deductibility of Traditional IRA contributions based on the income phase-outs for workplace plan participants.
SEP IRA Considerations
Employers make SEP IRA contributions on behalf of employees, and these contributions don't count against your personal max IRA deposit limit. If your employer contributes $20,000 to your SEP IRA in 2026, you can still contribute $7,000 to a Traditional or Roth IRA in your own name.
The SEC provides educational resources explaining how different IRA types work and their respective contribution rules, helping investors understand these distinctions.
Recent Legislative Changes Affecting Contributions
Congress periodically adjusts retirement savings rules through major legislation. The SECURE Act (2019) and SECURE 2.0 Act (2022) introduced several changes that affect retirement planning strategies, though the basic max IRA deposit limits have remained relatively stable.
SECURE 2.0 Highlights
While SECURE 2.0 primarily focused on employer-sponsored plans, several provisions indirectly affect IRA planning strategies. The CFP Board has published guidance on how these changes influence comprehensive financial planning.
Relevant SECURE 2.0 provisions:
- Increased RMD age to 73 (rising to 75 in 2033)
- Enhanced catch-up contribution rules for certain employer plans
- Emergency savings provisions
- Student loan matching provisions for workplace plans
- Penalty-free withdrawals for certain emergencies
Recent final regulations clarified implementation details for several SECURE 2.0 provisions, particularly regarding catch-up contributions in employer plans, though these specific rules don't directly change the max IRA deposit for Traditional and Roth IRAs.
Inflation Adjustments
The IRS reviews contribution limits annually and adjusts them based on cost-of-living increases. While the max IRA deposit for 2026 remains at $7,000, future years may see increases as inflation warrants. AARP regularly updates guidance on these annual adjustments to help retirees and near-retirees plan effectively.
Monitoring these adjustments each fall allows you to plan your contribution strategy for the upcoming year and ensure you're maximizing available tax-advantaged savings opportunities.
Contribution Strategies for Different Life Stages
Your optimal approach to the max IRA deposit evolves throughout your career and life circumstances. Tailoring your strategy to your current situation while maintaining flexibility for future changes creates a more resilient retirement plan.
Early Career (20s-30s)
Young professionals often benefit most from Roth IRA contributions, even if Traditional IRA contributions would be tax-deductible. Current tax rates are likely lower than future rates, making tax-free growth particularly valuable over a 30-40 year time horizon.
Starting with consistent contributions, even if below the max IRA deposit initially, establishes positive savings habits. Increasing contributions as income grows ensures you reach the maximum allowable amount as soon as financially feasible.
Mid-Career (40s-50s)
Peak earning years often coincide with peak contribution capacity. Maximizing the max IRA deposit becomes more achievable, and catch-up contributions after age 50 provide an additional boost precisely when retirement planning becomes more urgent.
This life stage also frequently involves balancing retirement savings with other goals like college funding or caring for aging parents. Prioritizing retirement contributions, particularly when employer matches are involved, typically serves long-term financial wellness best.
Pre-Retirement (55-65)
The final decade before retirement represents a critical window for maximizing the max IRA deposit and making strategic decisions about Traditional versus Roth contributions. Tax planning becomes particularly important as you model your expected retirement income sources and marginal tax rates.
Converting Traditional IRA assets to Roth IRAs during lower-income years, while still making annual contributions up to the max IRA deposit, can create valuable tax diversification for retirement. This strategy requires careful analysis of current versus future tax brackets and benefits from professional guidance.
Understanding and maximizing your max IRA deposit each year represents a cornerstone of sound retirement planning, though navigating contribution limits, income phase-outs, and strategic timing requires careful attention to evolving regulations and your personal financial situation. Whether you're just beginning your retirement savings journey or fine-tuning your strategy as retirement approaches, working with a fiduciary advisor ensures your IRA contributions align with your broader financial goals. Brookwood Investment Group offers personalized retirement planning guidance to help you navigate contribution strategies, tax optimization, and long-term wealth management tailored to your unique circumstances.
