Federal employees have access to one of the most comprehensive retirement systems in the country through the Federal Employees Retirement System. Understanding how your fers retirement pension works is essential for making informed decisions about your financial future. This system, which replaced the Civil Service Retirement System for most federal workers hired after 1983, provides a foundation for retirement income that coordinates with Social Security and the Thrift Savings Plan. Whether you're beginning your federal career or approaching retirement eligibility, knowing the mechanics of your pension benefit can help you plan effectively and avoid costly mistakes.
Understanding the FERS Three-Tiered Structure
The fers retirement pension operates as one component of a three-part retirement system designed to provide federal employees with comprehensive retirement security. The Federal Employees Retirement System combines a basic annuity, Social Security benefits, and the Thrift Savings Plan to create multiple income streams during retirement.
The Basic Annuity Component
Your basic annuity represents the core pension benefit calculated based on your years of creditable service and salary history. This defined benefit provides monthly payments for life once you meet eligibility requirements.
The three pillars work together in specific ways:
- Basic Annuity: A monthly pension payment guaranteed for life
- Social Security: Standard Social Security benefits earned through payroll taxes
- Thrift Savings Plan: A defined contribution plan similar to a 401(k)
Unlike many private sector employees who rely solely on personal savings and Social Security, federal workers benefit from this multi-layered approach to retirement income. Each component serves a distinct purpose in your overall retirement strategy.
Eligibility Requirements for FERS Retirement
The fers retirement pension becomes available when you meet specific age and service requirements that vary based on the type of retirement you pursue. Understanding these eligibility thresholds helps you plan your retirement timeline strategically.
Immediate Retirement Options
| Retirement Type | Minimum Age | Years of Service | Additional Requirements |
|---|---|---|---|
| Immediate (Voluntary) | 62 | 5 years | None |
| Immediate (Voluntary) | 60 | 20 years | None |
| Immediate (Voluntary) | MRA* | 30 years | None |
| Immediate (MRA+10) | MRA | 10 years | Reduced benefit |
| Special Provisions | 50 | 20 years | Law enforcement, firefighters, air traffic controllers |
*MRA (Minimum Retirement Age) ranges from 55 to 57 depending on your birth year.
Deferred and Postponed Retirement
If you leave federal service before meeting immediate retirement eligibility, you may qualify for deferred retirement. You can receive your fers retirement pension starting at age 62 with five years of service, though you cannot begin collecting payments until you reach that age.
Postponed retirement applies when you meet all requirements for immediate retirement but continue working. Your annuity calculation will reflect the additional service time and potentially higher salary.
Working with a financial advisor who specializes in retirement planning can help you evaluate the optimal timing for beginning your pension benefits based on your complete financial picture.
Calculating Your FERS Pension Benefit
The calculation methodology for your basic annuity uses a straightforward formula, but understanding the components ensures accurate retirement projections. Your fers retirement pension amount depends on three primary factors.
The High-3 Average Salary
Your high-3 average salary represents the highest average basic pay you earned during any consecutive 36-month period of service. This typically occurs during your final three years of employment, though not always.
The calculation includes:
- Basic salary (excluding overtime, bonuses, or locality pay in most cases)
- Any within-grade increases or promotions during the period
- The actual pay received during each pay period
Standard FERS Calculation Formula
For most federal employees retiring at age 62 or older with at least 20 years of service, the formula is:
1% × High-3 Average Salary × Years of Creditable Service
For those retiring before age 62 or with fewer than 20 years of service:
1% × High-3 Average Salary × Years of Creditable Service
For employees retiring at age 62 or older with 20+ years of service:
1.1% × High-3 Average Salary × Years of Creditable Service
Practical Calculation Examples
Consider a federal employee with a high-3 average salary of $95,000 who retires at age 62 with 25 years of service:
$95,000 × 0.011 × 25 = $26,125 annual pension ($2,177 per month)
The same employee retiring at age 60 would receive:
$95,000 × 0.01 × 25 = $23,750 annual pension ($1,979 per month)
This difference of $2,375 annually demonstrates why timing your retirement strategically matters for maximizing your fers retirement pension.
Special Categories and Enhanced Benefits
Certain federal positions qualify for enhanced retirement benefits that allow earlier retirement with more favorable calculation formulas. These special provisions recognize the unique demands of specific occupations.
Law Enforcement Officers and Firefighters
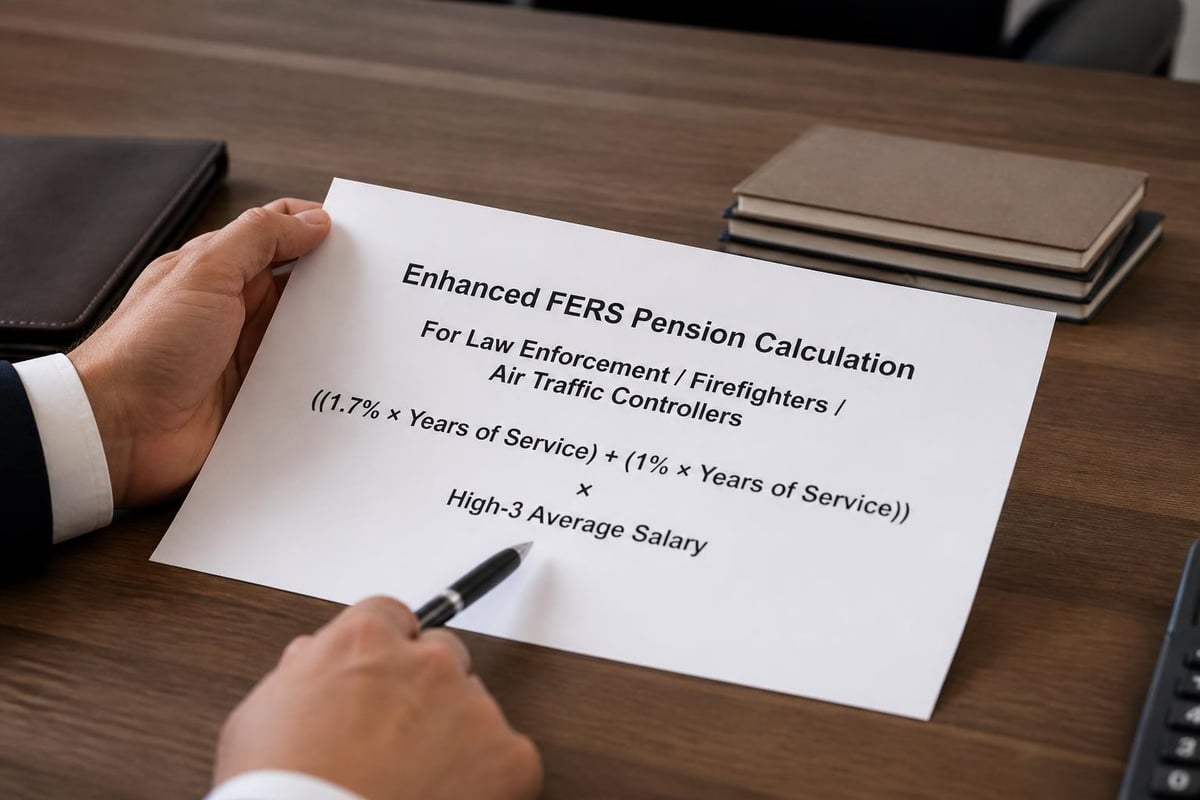
Federal law enforcement officers and firefighters can retire at age 50 with 20 years of service or at any age with 25 years of service. Their annuity calculation uses:
1.7% × High-3 Average Salary × First 20 Years + 1% × High-3 Average Salary × Years Beyond 20
Air Traffic Controllers
Air traffic controllers have similar enhanced benefits allowing retirement at age 50 with 20 years of service. The same enhanced calculation formula applies to their fers retirement pension.
Congressional Employees and Special Groups
The CSRS/FERS Handbook provides detailed information about other special category employees, including members of Congress, congressional staff, and certain other positions with modified benefit structures.
The FERS Retiree Annuity Supplement
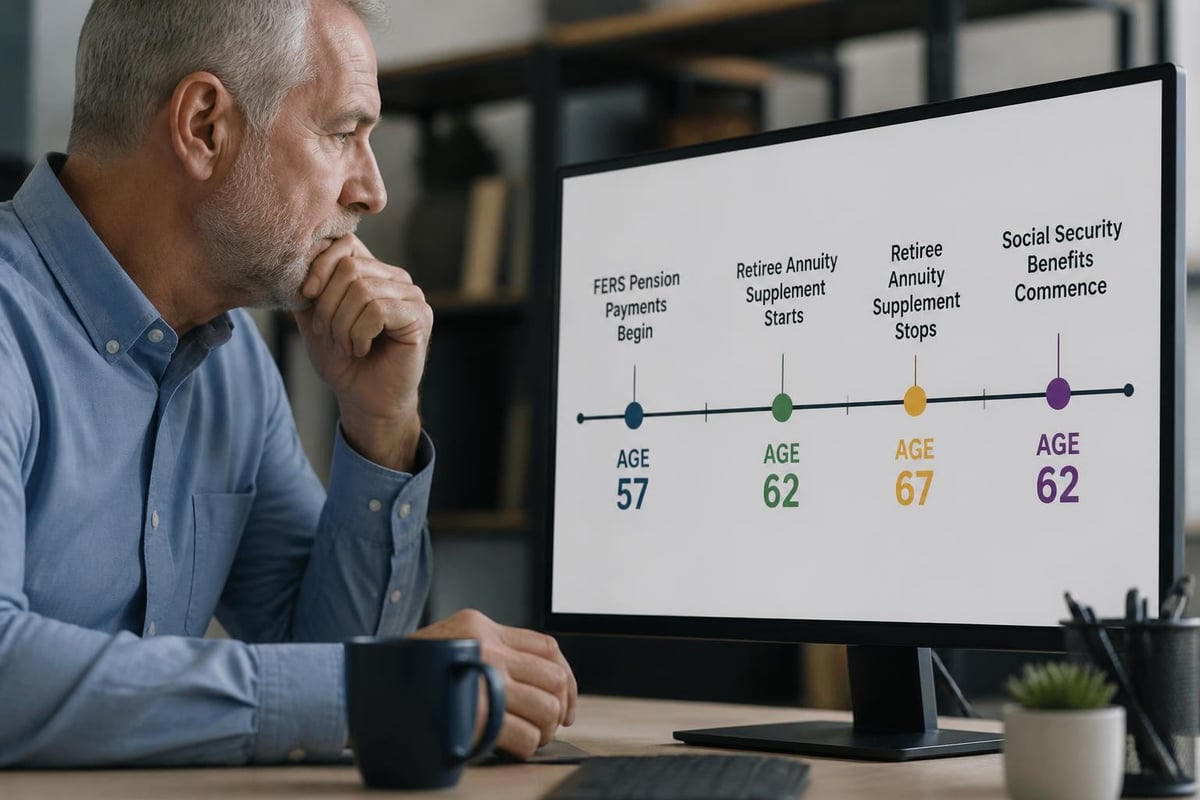
One of the most valuable yet frequently misunderstood aspects of the fers retirement pension is the Special Retirement Supplement (SRS). This temporary payment bridges the gap between your retirement date and Social Security eligibility at age 62.
Supplement Eligibility Requirements
You qualify for the supplement if you retire:
- At your minimum retirement age with 30 years of service
- At age 60 with 20 years of service
- Under special provisions for law enforcement, firefighters, or air traffic controllers
The supplement does not apply to:
- MRA+10 retirees
- Deferred retirement annuitants
- Those who retire after age 62
Calculating the Supplement Amount
The supplement approximates the Social Security benefit you earned during your federal service. The calculation estimates what your full Social Security benefit would be at age 62, then multiplies it by the fraction of your career spent in federal service.
Estimated Social Security Benefit × (Years of FERS Service ÷ 40)
If your estimated Social Security benefit at age 62 is $1,500 and you have 30 years of FERS service:
$1,500 × (30 ÷ 40) = $1,125 monthly supplement
Earnings Test Limitations
The supplement is subject to the Social Security earnings test. In 2026, if you earn more than $23,400 annually from wages or self-employment, your supplement reduces by $1 for every $2 earned above the threshold. This can eliminate the supplement entirely for those who continue working in the private sector.
Survivor Benefits and FERS Elections
Your fers retirement pension includes provisions for protecting your spouse or former spouse through survivor annuities. These decisions typically become irrevocable after retirement, making pre-retirement planning essential.
Spousal Survivor Benefit Options
| Survivor Benefit | Reduction to Your Annuity | Survivor Receives |
|---|---|---|
| Full (50%) | 10% reduction | 50% of unreduced annuity |
| Partial (25%) | 5% reduction | 25% of unreduced annuity |
| None | No reduction | Nothing |
The standard election provides your surviving spouse with 50% of your unreduced annuity in exchange for a permanent 10% reduction in your monthly payment. Married employees must obtain spousal consent in writing to elect anything less than the full survivor benefit.
Former Spouse Considerations
Court orders from divorce proceedings may require you to provide a former spouse survivor annuity. These court-ordered benefits take precedence over subsequent elections and can affect the benefits available to a current spouse.
Planning for these decisions as part of comprehensive estate planning helps ensure your choices align with your overall wealth transfer goals.
Cost of Living Adjustments
The fers retirement pension includes automatic cost-of-living adjustments (COLAs) to help preserve purchasing power throughout retirement. However, FERS COLAs differ significantly from the adjustments provided under the older CSRS system.
FERS COLA Formula
FERS retirees receive COLAs based on changes in the Consumer Price Index, but with important limitations:
- If CPI increase is 2% or less: Full COLA applied
- If CPI increase is 2-3%: COLA is 2%
- If CPI increase exceeds 3%: COLA is CPI minus 1 percentage point
For example, if inflation measures 4.5%, FERS retirees receive a 3.5% COLA, while CSRS retirees would receive the full 4.5%.
COLA Eligibility Timing
You become eligible for COLAs one year after your retirement date, not immediately upon retirement. Those who retire under disability provisions receive COLAs at age 62.
Coordinating FERS with Social Security
Your fers retirement pension works in conjunction with Social Security benefits, but understanding how these programs interact helps you optimize total retirement income. Federal employees pay into Social Security through FICA taxes, earning benefits just like private sector workers.
Impact of Government Pension Offset
The Government Pension Offset (GPO) generally does not affect FERS employees because they pay Social Security taxes. However, if you have non-FERS service (such as time under CSRS) that was not subject to Social Security taxes, GPO could reduce spousal or survivor Social Security benefits.
Windfall Elimination Provision
Similarly, the Windfall Elimination Provision (WEP) primarily affects those with mixed CSRS and FERS service. Understanding federal tax implications of both your pension and Social Security helps you plan for the complete tax picture in retirement.
The Thrift Savings Plan Component
While not technically part of your fers retirement pension, the Thrift Savings Plan represents the self-directed component of the FERS three-tiered system. This defined contribution plan allows you to accumulate additional retirement assets through payroll contributions.
TSP Matching Contributions
FERS employees receive automatic agency contributions:
- 1% automatic contribution (even if you contribute nothing)
- Dollar-for-dollar match on the first 3% you contribute
- 50 cents on the dollar for the next 2% you contribute
This means contributing 5% of your salary generates a total contribution of 10% when including the agency match and automatic contribution.
Integration with Your Pension Strategy
The TSP provides flexibility that your defined benefit pension lacks. You control investment allocations, withdrawal timing, and can potentially leave assets to heirs. Many federal employees find that their TSP balance eventually exceeds their pension's present value, making it a critical component of retirement planning.
Decisions about rolling pension lump sums into an IRA and coordinating withdrawals from multiple accounts benefit from professional guidance tailored to your specific situation.
Tax Implications of FERS Pension Payments
Your fers retirement pension is subject to federal income tax, and potentially state income tax depending on your residence. Understanding the tax treatment helps you plan for net retirement income.
Federal Taxation of Annuity Payments
The entire amount of your FERS annuity is taxable as ordinary income because your contributions were made with pre-tax dollars. You'll receive a Form 1099-R each January showing the total amount paid during the previous year.
Unlike Social Security benefits, which may be partially tax-free, your FERS pension has no tax-free portion for most employees.
State Tax Considerations
State taxation of federal pensions varies significantly:
- Some states exempt all federal pension income
- Others provide partial exemptions or deductions
- A few states tax federal pensions the same as any other income
If you plan to relocate in retirement, state tax treatment of your fers retirement pension should factor into your decision about where to establish residency.
Withholding Elections
You can adjust federal income tax withholding from your annuity payments using Form W-4P. Many retirees initially underwithhold, creating unexpected tax bills in their first year of retirement. Conservative withholding combined with quarterly estimated tax payments can prevent this issue.
Disability Retirement Under FERS
Federal employees who become unable to perform their job duties due to medical conditions may qualify for disability retirement, providing access to their fers retirement pension earlier than standard retirement eligibility allows.
Disability Retirement Requirements
To qualify, you must:
- Have completed at least 18 months of creditable civilian service
- Be unable to perform useful and efficient service in your current position
- Have your condition expected to last at least one year
- Apply while still employed or within one year of separation
Disability Benefit Calculations
The computation for disability retirement differs from standard retirement:
First Year: 60% of high-3 average salary minus 100% of any Social Security disability benefits
After First Year: 40% of high-3 average salary minus 60% of Social Security disability benefits
At age 62, the Office of Personnel Management recalculates your benefit using the standard FERS formula as if you had continued working until age 62 at the same grade and step.
Application Process and Timing
Applying for your fers retirement pension requires careful attention to deadlines and procedures. The process typically begins 60 to 90 days before your intended retirement date, though you can submit applications up to one year in advance for voluntary retirement.
Required Documentation
Your retirement application package includes:
- SF-3107 (Application for Immediate Retirement)
- SF-2801 (Application for Death Benefits) if you're married
- Spousal consent forms if electing less than full survivor benefit
- Birth certificates and marriage certificates
- Military service documentation if claiming credit
Processing Timeline
OPM typically processes retirement applications within 60 days, though complex cases may take longer. During this interim period, you receive interim payments equal to the estimated annuity amount, subject to later adjustment.
Understanding fiduciary planning principles helps ensure that your retirement timeline aligns with your broader financial goals rather than just administrative convenience.
Common FERS Pension Mistakes to Avoid
Even experienced federal employees sometimes make errors that reduce their fers retirement pension or create unnecessary complications. Awareness of these common pitfalls helps you avoid them.
Underestimating the Impact of Unused Sick Leave
Many federal employees don't realize that unused sick leave at retirement increases your creditable service for annuity calculations. If you have 2,000 hours of unused sick leave, this adds one year to your service computation, potentially increasing your pension by thousands of dollars annually.
Failing to Review Your Benefits Estimate
The Office of Personnel Management provides retirement estimates that sometimes contain errors. Review your Personal Statement of Benefits regularly and request corrections promptly if you identify discrepancies in your service history.
Timing Mistakes with the Annuity Supplement
Resources from organizations like NARFE highlight that earning too much in post-retirement employment can eliminate your Special Retirement Supplement entirely. Understanding the earnings test before accepting post-retirement work prevents surprise reductions.
Not Coordinating with Other Income Sources
Your fers retirement pension represents just one piece of your retirement income. Failing to coordinate pension timing with Social Security claims, TSP withdrawals, and other income sources may result in suboptimal tax outcomes or unnecessary benefit reductions.
Strategic Considerations for Federal Employees
Maximizing the value of your fers retirement pension requires strategic thinking throughout your federal career, not just in the years immediately before retirement.
Military Service Credit Purchases
Veterans with military service can increase their FERS annuity by making a deposit to receive credit for their military time. This can be particularly valuable if you have several years of military service.
The deposit equals 3% of your military base pay plus interest. While the cost increases the longer you wait, purchasing this credit can substantially increase your pension if you're close to a higher eligibility threshold.
Part-Time Service Considerations
Part-time federal employment provides retirement credit proportional to the hours worked. Ten years of half-time employment equals five years of full-time credit. Understanding how part-time service affects your annuity calculation helps you evaluate career decisions that involve schedule changes.
Phased Retirement Options
The FERS phased retirement program allows eligible employees to work part-time while receiving a partial annuity. This bridges full-time employment and complete retirement, though not all agencies offer this option.
Long-Term Planning with Your FERS Pension
Your fers retirement pension provides guaranteed lifetime income, making it a valuable foundation for retirement security. However, integrating this benefit into a comprehensive financial plan requires looking beyond just the monthly payment amount.
Inflation Protection Considerations
While FERS provides COLAs, the diet COLA formula means your pension won't keep pace with inflation during high-inflation periods. Building a diversified investment portfolio that includes growth assets helps offset this limitation over a potentially 30-year retirement.
Longevity Planning
Because your FERS annuity continues for life, it provides valuable longevity insurance. However, survivor benefits reduce during your lifetime, and if your spouse predeceases you, the reduction continues without the corresponding benefit being paid to anyone.
Evaluating whether the survivor benefit represents the most cost-effective way to provide for your spouse compared to life insurance or other strategies requires personalized analysis.
Healthcare Bridge to Medicare
Federal employees who retire before age 65 can continue Federal Employees Health Benefits (FEHB) into retirement. This continuation bridges the gap until Medicare eligibility and represents substantial value that should factor into your retirement timing decision.
Understanding current trends in federal retirement systems helps you anticipate potential policy changes that might affect future benefit structures.
Integrating Professional Financial Guidance
The complexity of the fers retirement pension, combined with its interaction with Social Security, the TSP, and your personal financial situation, often warrants professional guidance. Working with advisors who understand federal benefits helps you avoid costly mistakes.
Questions to Ask Advisors
When seeking professional assistance with FERS planning:
- Do you regularly work with federal employees?
- Are you familiar with the Special Retirement Supplement and its earnings test?
- How do you coordinate FERS pension timing with Social Security claiming strategies?
- What experience do you have with the specific tax planning issues federal retirees face?
Areas Where Professional Guidance Adds Value
Key planning areas that benefit from expert input include:
- Optimal timing for beginning your annuity versus continuing work
- Survivor benefit elections and their alternatives
- Tax-efficient withdrawal sequencing from multiple accounts
- Estate planning considerations when pension benefits and TSP balances are significant
Working with a fiduciary advisor ensures that recommendations prioritize your interests rather than commission-based product sales.
Understanding your fers retirement pension empowers you to make informed decisions that align with your retirement timeline and financial goals. The interaction between your basic annuity, Social Security benefits, and Thrift Savings Plan creates opportunities for optimization that require careful analysis of your unique circumstances. Brookwood Investment Group specializes in helping federal employees navigate these complex decisions through personalized retirement planning that considers your complete financial picture. Schedule a consultation with Brookwood Investment Group to explore how strategic planning can help you maximize the value of your federal benefits and build confidence in your retirement readiness.
