High-income professionals often find themselves locked out of direct Roth IRA contributions due to income limitations. The ira backdoor roth strategy offers a legitimate workaround, allowing earners above the income threshold to access the tax-free growth and withdrawal benefits that Roth accounts provide. This approach has become increasingly popular among those seeking to diversify their retirement tax strategies, particularly as they approach their peak earning years. Understanding the mechanics, tax implications, and potential pitfalls of this strategy is essential for anyone considering implementation in 2026.
Understanding the IRA Backdoor Roth Strategy
The ira backdoor roth technique involves a two-step process that circumvents the income restrictions on direct Roth IRA contributions. For 2026, single filers earning above $153,000 and married couples filing jointly with income exceeding $228,000 face reduced contribution limits or complete phase-outs for direct Roth contributions.
The strategy works by first making a nondeductible contribution to a traditional IRA, then converting that contribution to a Roth IRA. Since there are no income limits on making nondeductible traditional IRA contributions or converting traditional IRAs to Roth IRAs, this approach provides an effective pathway for high earners.
Why High Earners Choose This Strategy
Tax diversification represents one of the primary motivations for pursuing an ira backdoor roth conversion. Many high-income professionals already maximize pre-tax contributions through 401(k) plans and may benefit from balancing their retirement portfolio with tax-free Roth assets.
Additional advantages include:
- Tax-free qualified withdrawals in retirement
- No required minimum distributions during the account owner's lifetime
- Flexibility for estate planning purposes
- Continued contributions regardless of age
- Potential for tax-free legacy wealth transfer
Step-by-Step Implementation Process
Executing an ira backdoor roth conversion requires careful attention to timing and documentation. The process may seem straightforward, but several technical details demand precision to maintain compliance and optimize tax treatment.
Opening the Necessary Accounts
Before initiating your first backdoor Roth conversion, ensure you have both a traditional IRA and a Roth IRA established at your chosen financial institution. Many investors working with fiduciary advisors benefit from coordinating account setup with their broader retirement planning strategy.
Account preparation checklist:
- Open a traditional IRA if you don't already have one
- Establish a Roth IRA at the same or different institution
- Verify your custodian supports conversion transactions
- Review fee structures for contributions and conversions
- Confirm online access for transaction monitoring
Making Your Nondeductible Contribution
The first step involves contributing to your traditional IRA. For 2026, the contribution limit is $7,000 for those under age 50, with an additional $1,000 catch-up contribution for individuals aged 50 and older. You can learn more about contribution rules in IRS Publication 590-A, which details all IRA contribution requirements.
The contribution must be classified as nondeductible because high earners typically cannot deduct traditional IRA contributions when they're covered by an employer retirement plan. This nondeductible status becomes critical for the conversion step and subsequent tax reporting.
Executing the Roth Conversion
After making your traditional IRA contribution, you'll initiate the conversion to your Roth IRA. Many financial institutions, including Vanguard and Fidelity, provide streamlined online processes for completing conversions.
The timing between contribution and conversion sparks considerable debate. While some advisors recommend immediate conversion, others suggest waiting until investments settle or tax years change. The key consideration is minimizing earnings in the traditional IRA before conversion, which reduces taxable income generated by the conversion.
Tax Implications and Reporting Requirements
Understanding the tax consequences of an ira backdoor roth conversion is essential for compliance and accurate planning. The conversion itself triggers reporting obligations that extend across multiple tax years when done properly.
The Pro-Rata Rule Challenge
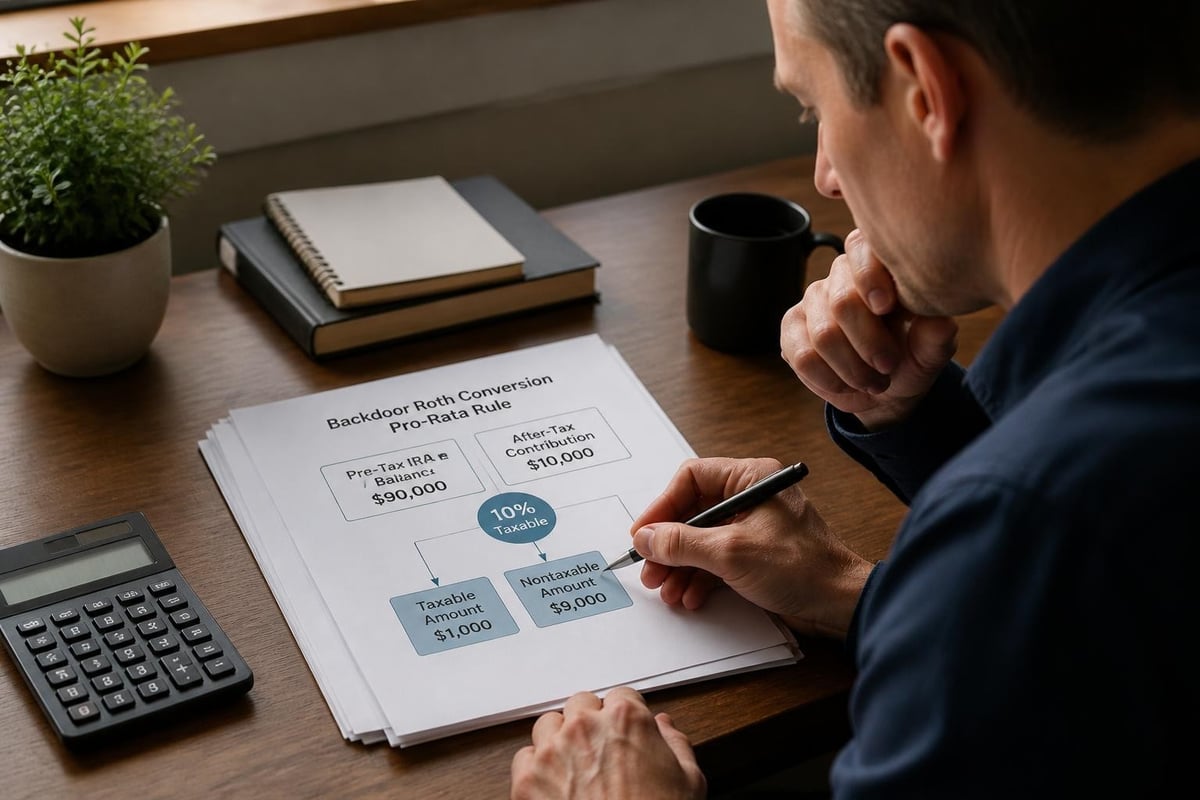
The pro-rata rule represents the most significant complication for many investors attempting an ira backdoor roth conversion. This IRS regulation requires that any conversion be treated as coming proportionally from both pre-tax and after-tax dollars across all your traditional, SEP, and SIMPLE IRAs combined.
| Scenario | Traditional IRA Balance | Nondeductible Contribution | Pre-Tax Portion | After-Tax Portion |
|---|---|---|---|---|
| Clean conversion | $0 | $7,000 | 0% | 100% |
| Existing pre-tax IRA | $63,000 | $7,000 | 90% | 10% |
| Large rollover IRA | $350,000 | $7,000 | 98% | 2% |
As the table illustrates, existing pre-tax IRA balances significantly dilute the tax efficiency of the backdoor Roth strategy. Individuals with substantial traditional IRA holdings may face unexpected tax bills when executing conversions.
Form 8606 Filing Requirements
Every ira backdoor roth conversion requires filing IRS Form 8606 with your tax return. This form tracks your basis in traditional IRAs and documents both the nondeductible contribution and the subsequent conversion.
Critical filing points:
- Part I reports nondeductible contributions to traditional IRAs
- Part II documents conversions from traditional to Roth IRAs
- Errors or omissions can result in double taxation
- Maintain records for all years with nondeductible contributions
- Professional tax preparation becomes increasingly valuable
Strategic Considerations for 2026
The landscape surrounding the ira backdoor roth continues to evolve, with legislative proposals periodically threatening to eliminate this strategy. While no changes have been enacted as of 2026, staying informed about potential modifications remains important for long-term planning.
Timing Your Contributions and Conversions
You can make IRA contributions for a given tax year anytime from January 1 of that year through the tax filing deadline (typically April 15 of the following year). This extended timeline provides flexibility for strategic planning.
Conversion timing, however, operates differently. Conversions must occur within the calendar year to be reported on that year's tax return. This distinction allows for interesting planning opportunities when coordinating contributions and conversions across tax years.
Coordinating with Employer Retirement Plans
High earners often have access to 401(k) plans that accept incoming rollovers. Charles Schwab’s educational resources explain how rolling existing traditional IRA balances into an employer plan can eliminate the pro-rata rule obstacle, making the ira backdoor roth strategy significantly more tax-efficient.
This reverse rollover approach requires:
- Confirming your employer plan accepts incoming rollovers
- Verifying only pre-tax dollars transfer (not nondeductible contributions)
- Completing the rollover before executing your Roth conversion
- Documenting the transaction sequence for tax reporting
Those considering a pension lump sum rollover to IRA should coordinate carefully to maintain the tax advantages of the backdoor Roth strategy.
Common Mistakes to Avoid
Even experienced investors can stumble when implementing an ira backdoor roth conversion. Awareness of frequent errors helps ensure smooth execution and optimal tax treatment.
Investment Selection Before Conversion
Some investors immediately invest their traditional IRA contributions in growth-oriented assets, hoping to maximize returns before conversion. This approach creates unnecessary tax complexity, as any earnings generated before conversion become taxable income.
Best practices for contribution timing:
- Consider money market funds or settlement accounts initially
- Minimize the time between contribution and conversion
- Invest aggressively after conversion is complete
- Track any earnings for accurate tax reporting
- Document each step with account statements
Forgetting About Inherited IRAs
The pro-rata rule applies to traditional, SEP, and SIMPLE IRAs that you own, but it does not include inherited IRAs. This distinction can save taxpayers who maintain separate inherited IRA accounts from unexpected tax consequences when executing an ira backdoor roth.
Overlooking State Tax Implications
While federal tax treatment of conversions follows consistent rules, state taxation varies considerably. Some states do not recognize Roth conversions the same way the IRS does, potentially creating additional tax liabilities or different reporting requirements.
Residents of states with high income tax rates should evaluate state-specific consequences before proceeding. Working with CPA financial advisors who understand both federal and state tax codes can prevent costly surprises.
Advanced Strategies and Alternatives
Beyond the basic ira backdoor roth conversion, several advanced techniques and related strategies merit consideration for high-income earners seeking to maximize retirement savings.
Mega Backdoor Roth Conversions
For those with access to 401(k) plans that allow after-tax contributions and in-service distributions, the mega backdoor Roth strategy can facilitate significantly larger conversions. This approach can enable contributions exceeding $40,000 annually, far surpassing the standard $7,000 IRA limit.
Mega backdoor Roth requirements:
| Requirement | Description | Verification Steps |
|---|---|---|
| After-tax contributions | Plan must permit beyond standard deferrals | Review plan document Section 401(m) |
| In-service distribution | Allows withdrawal while still employed | Confirm with HR or plan administrator |
| Conversion pathway | Direct rollover to Roth IRA or in-plan conversion | Test with small trial transaction |
| Contribution room | Total limit minus other contributions | Calculate: $69,000 – employer match – deferrals |
Spousal IRA Backdoor Conversions
Married couples can potentially double their ira backdoor roth contributions by utilizing spousal IRA provisions. Even if one spouse has little or no earned income, they can contribute to their own IRA based on the couple's combined earned income.
This strategy requires:
- Filing married filing jointly tax status
- Sufficient combined earned income
- Separate IRA accounts for each spouse
- Independent tracking and Form 8606 filing for each person
- Careful documentation of each spouse's contribution basis
Regulatory Background and Investor Protections
Understanding the regulatory framework surrounding Roth IRAs and conversions helps investors make informed decisions aligned with established rules and protections. The SEC’s investor education resources provide foundational knowledge about Roth IRA features and regulatory oversight.
The ira backdoor roth strategy exists within a well-defined legal framework, though it operates through what some characterize as a legislative gap rather than explicitly authorized legislation. The Tax Foundation’s research on retirement account taxation examines broader policy considerations around Roth treatment and retirement savings incentives.
Legislative Risk Considerations
Congress has periodically considered proposals to eliminate the ira backdoor roth strategy, most recently in 2021 and 2022 budget reconciliation discussions. While these proposals have not become law, investors should remain aware that future legislation could modify or eliminate this planning technique.
Current proposals typically include:
- Prohibiting conversions of after-tax contributions in IRAs
- Eliminating all Roth conversions for high-income taxpayers
- Restricting mega backdoor Roth strategies in employer plans
- Implementing prospective effective dates rather than retroactive changes
Staying informed through trusted financial advisors helps ensure timely adjustments to changing regulations while taking advantage of current opportunities.
Integration with Comprehensive Financial Planning
The ira backdoor roth conversion should not exist in isolation but rather as one component of a coordinated retirement and tax strategy. High-income professionals benefit from viewing this technique within their broader financial picture.
Coordinating with Estate Planning
Roth IRAs offer unique advantages for estate planning purposes. Unlike traditional IRAs, Roth accounts have no required minimum distributions during the owner's lifetime, allowing assets to compound tax-free for longer periods. Beneficiaries who inherit Roth IRAs can take distributions tax-free, creating valuable legacy planning opportunities.
Estate planning integration points:
- Determine which beneficiaries benefit most from inherited Roth assets
- Consider Roth conversions as part of lifetime gifting strategies
- Evaluate the impact on estate tax calculations for large estates
- Coordinate with trust structures when appropriate
- Review beneficiary designations regularly for alignment with goals
Tax Planning Across Multiple Years
Sophisticated implementation of the ira backdoor roth involves considering conversions within your multi-year tax strategy. Years with lower income, higher deductions, or other tax planning opportunities may present ideal conversion timing.
Factors influencing multi-year planning include:
- Business losses or reduced income years
- Large charitable deductions
- Transition between career phases
- Relocation to lower-tax states
- Retirement before Social Security commencement
The ira backdoor roth strategy provides high-income earners with valuable access to Roth IRA benefits despite income restrictions on direct contributions. While the technique involves careful execution and ongoing tax reporting, the potential for decades of tax-free growth makes it a consideration for many professionals seeking to optimize their retirement planning. Brookwood Investment Group LLC offers personalized guidance on backdoor Roth conversions as part of comprehensive retirement and tax planning strategies, helping clients navigate the complexities while coordinating with their broader financial goals. Working with a fiduciary advisor ensures your backdoor Roth strategy aligns with your unique circumstances and long-term objectives.
