Navigating a principal financial 401k withdrawal requires careful planning and a thorough understanding of distribution rules, tax implications, and timing considerations. Whether you're approaching retirement age, facing a financial hardship, or simply exploring your options, understanding the withdrawal process from your Principal Financial 401(k) account helps you make informed decisions that align with your long-term financial objectives. This comprehensive guide explores the mechanics of Principal withdrawals, regulatory requirements, and strategic considerations to help you preserve your retirement savings while meeting your current financial needs.
Understanding Principal Financial 401k Distribution Options
Principal Financial Group administers retirement plans for thousands of employers nationwide, and each plan may have unique provisions governing when and how participants can access their funds. The principal financial 401k withdrawal process begins with understanding your specific plan's rules and the broader federal regulations that govern all qualified retirement accounts.
Types of Withdrawals Available
Principal Financial offers several distribution methods, each with distinct eligibility requirements and tax consequences:
- Hardship withdrawals for immediate and heavy financial needs
- In-service withdrawals for participants who have reached age 59½ while still employed
- Separation from service distributions after leaving your employer
- Required Minimum Distributions (RMDs) beginning at age 73 for those born in 1960 or later
- Loans as an alternative to direct withdrawals (not technically a distribution)
The Principal Financial help center provides plan-specific guidance on which options apply to your individual circumstances. Working with fiduciary advisory services ensures you receive personalized advice that prioritizes your best interests throughout the withdrawal process.
Age-Based Withdrawal Rules
Your age significantly impacts the consequences of a principal financial 401k withdrawal. Understanding these age thresholds helps you plan distributions strategically:
| Age Range | Withdrawal Status | Tax Penalty | Key Considerations |
|---|---|---|---|
| Under 55 | Early withdrawal | 10% penalty + income tax | Limited exceptions apply |
| 55-59 | Rule of 55 may apply | Potentially no penalty | Only if separated from service |
| 59½+ | Qualified distribution | Income tax only | No early withdrawal penalty |
| 73+ | RMDs required | 50% penalty if not taken | Annual mandatory withdrawals |
The IRS guidance on Required Minimum Distributions outlines the federal mandates that apply regardless of which financial institution holds your 401(k). These rules have evolved recently with the SECURE 2.0 Act, making professional guidance particularly valuable for those approaching RMD age.
Hardship Withdrawal Criteria and Process
The IRS establishes specific criteria for 401k hardship distributions that must be met before Principal Financial can approve a hardship withdrawal request. These distributions represent an immediate and heavy financial need that cannot be relieved through other reasonably available resources.
Qualifying Hardship Reasons
Principal Financial typically recognizes these IRS-approved hardship categories:
- Medical expenses for you, your spouse, dependents, or primary beneficiary
- Costs directly related to purchasing your principal residence (excluding mortgage payments)
- Tuition and related educational fees and room and board for the next 12 months
- Payments necessary to prevent eviction or foreclosure on your principal residence
- Funeral expenses for you, your spouse, dependents, children, or primary beneficiary
- Certain expenses to repair damage to your principal residence
- Expenses and losses due to federally declared disasters
Each hardship withdrawal request requires documentation demonstrating both the need and the amount required. Your employer's plan document may impose additional restrictions beyond these federal requirements.
Tax Consequences of Hardship Withdrawals
A principal financial 401k withdrawal taken as a hardship distribution triggers immediate tax liabilities. The distributed amount counts as ordinary income in the year you receive it, and if you're under age 59½, a 10% early withdrawal penalty typically applies unless an exception qualifies.
Important considerations:
- Hardship withdrawals cannot be repaid to the plan
- You may be suspended from making plan contributions for six months following the withdrawal
- The distribution reduces your retirement savings permanently
- State income taxes may also apply depending on your residence
Understanding taxation of retirement income helps you calculate the true after-tax cost of accessing these funds. Many individuals discover that a hardship withdrawal provides less net cash than anticipated once taxes and penalties are considered.
Strategic Timing for Principal Financial 401k Withdrawals
When you initiate a principal financial 401k withdrawal significantly impacts your overall financial picture. Strategic timing considerations extend beyond simply avoiding penalties to encompass tax efficiency, market conditions, and cash flow management.
Retirement Age Distributions
For those who have separated from service and reached age 59½ or older, withdrawal timing becomes more flexible but no less important. Consider these factors:
- Tax bracket management: Spreading withdrawals across multiple years may keep you in lower tax brackets
- Medicare premium impacts: Large distributions can increase Modified Adjusted Gross Income (MAGI), potentially raising Medicare Part B and D premiums
- Social Security taxation: Higher income from 401(k) withdrawals may cause more of your Social Security benefits to become taxable
- State residency: Retiring to a state with no income tax before taking distributions can generate substantial savings
Required Minimum Distribution Compliance
Once you reach age 73 (for those born in 1960 or later), federal law mandates annual RMDs from your Principal Financial 401(k) unless you're still working for the plan sponsor and don't own 5% or more of the company. The first RMD must be taken by April 1 of the year following the year you turn 73, with subsequent distributions due by December 31 each year.
Calculating your RMD involves dividing your prior year-end account balance by the IRS life expectancy factor for your age. Principal Financial typically provides RMD calculations and can process systematic distributions to ensure compliance. The penalty for missing an RMD is severe: 50% of the amount that should have been withdrawn.
Working with professionals who specialize in retirement planning and estate planning ensures your withdrawal strategy coordinates with your broader financial plan and considers multi-year tax optimization opportunities.
Alternative Options to Direct Withdrawals
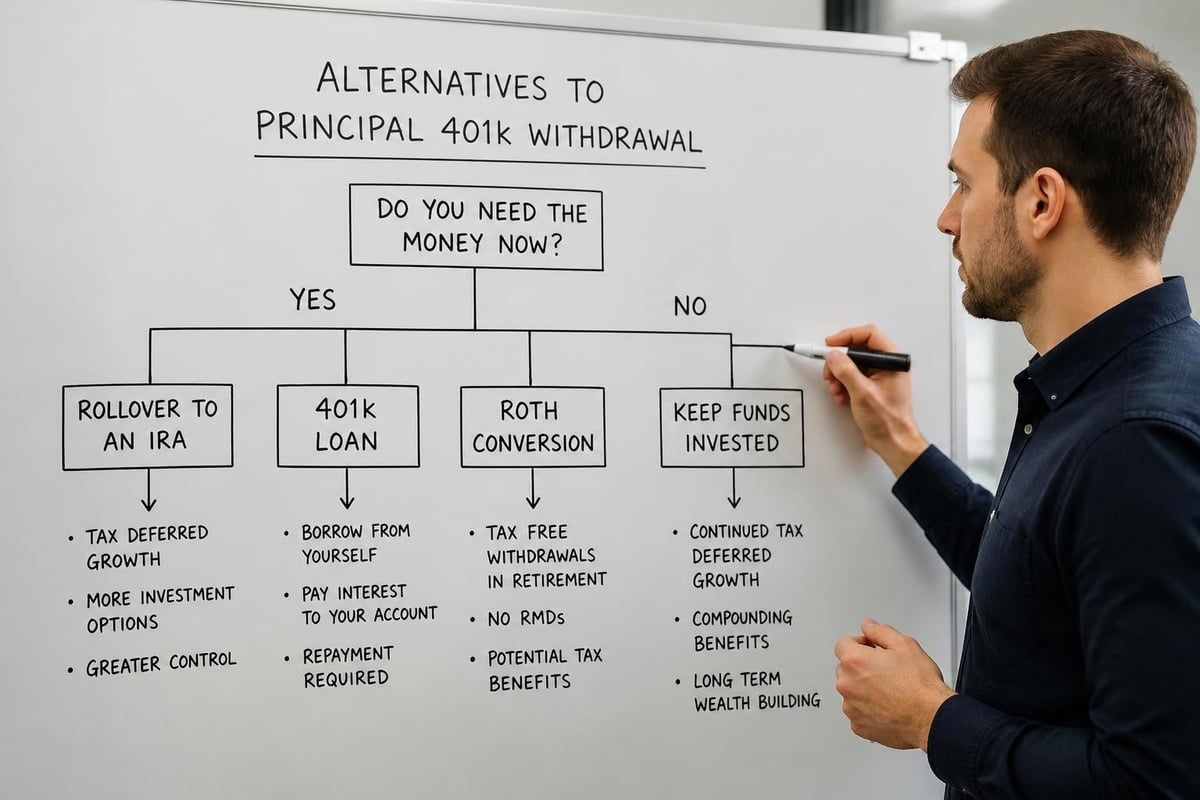
Before proceeding with a principal financial 401k withdrawal, evaluate these alternatives that may better serve your financial objectives:
Rollover to IRA
Rolling your Principal Financial 401(k) to an Individual Retirement Account offers several advantages:
- Expanded investment options beyond your employer plan's menu
- Consolidated management of multiple retirement accounts
- Continued tax-deferral without triggering immediate taxes
- Potential fee reduction depending on IRA provider selection
- Estate planning flexibility with more beneficiary designation options
The rollover process through Principal’s distribution learning center can be completed as a direct trustee-to-trustee transfer, avoiding tax withholding and the risk of an inadvertent taxable distribution. This option proves particularly valuable for those changing jobs or retiring who want to maintain their retirement savings while gaining more control over investment decisions.
401(k) Loan Provisions
If your plan permits loans, borrowing from your Principal Financial 401(k) allows access to funds without triggering taxes or penalties:
| Feature | 401(k) Loan | 401(k) Withdrawal |
|---|---|---|
| Tax impact | None if repaid | Immediate taxation |
| Early penalty | None if repaid | 10% if under 59½ |
| Repayment | Required (typically 5 years) | Not allowed |
| Impact on savings | Temporary | Permanent |
| Interest paid | To yourself | N/A |
Loans generally allow you to borrow up to 50% of your vested balance or $50,000, whichever is less. Interest rates typically approximate prime rate plus 1-2%. However, if you separate from service with an outstanding loan balance, the remaining amount typically becomes due, and unpaid balances convert to taxable distributions.
Roth Conversion Strategies
For those with access to both traditional and Roth options within their Principal Financial plan, or considering a rollover to a Roth IRA, strategic conversions can create tax-free withdrawal opportunities in the future. While conversions trigger immediate taxation on the converted amount, future qualified Roth distributions come out entirely tax-free.
This strategy particularly benefits individuals in lower tax brackets temporarily (perhaps during early retirement before RMDs begin or Social Security starts) who expect higher tax rates later. The Consumer Financial Protection Bureau’s retirement planning guidance emphasizes the importance of understanding all available options before accessing retirement funds.
Documentation and Processing Requirements
Initiating a principal financial 401k withdrawal requires specific documentation and follows a defined processing timeline. Understanding these requirements helps you plan accordingly and avoid unnecessary delays.
Required Documentation
Principal Financial typically requires:
- Completed distribution request form with notarized signature if required
- Spousal consent (if married and requesting certain distribution types)
- Tax withholding elections (federal and state)
- Hardship documentation if applicable (bills, eviction notices, medical statements)
- Beneficiary designations reviewed and updated
- Proof of age for certain distribution types
Your plan administrator can provide the specific forms required for your situation. Many plans now offer online distribution requests through Principal's participant portal, streamlining the process significantly.
Processing Timeline Expectations
Typical processing timeframes for principal financial 401k withdrawal requests:
- Standard distributions: 5-10 business days after receipt of complete documentation
- Hardship withdrawals: 7-14 business days due to additional review requirements
- Rollovers: 7-10 business days for direct transfers
- RMDs: Can be automated for systematic processing
Payment methods include direct deposit (fastest), paper check, or direct rollover to another qualified plan or IRA. Planning for these processing times ensures you receive funds when needed without unnecessary stress.
Tax Withholding and Reporting Obligations
Every principal financial 401k withdrawal creates tax reporting obligations for both you and the plan administrator. Understanding these requirements prevents surprises at tax time.
Mandatory Tax Withholding
Federal law requires 20% mandatory withholding on eligible rollover distributions paid directly to participants (rather than rolled to another qualified account). For non-eligible distributions like hardships or RMDs, you can elect withholding rates, though 10% federal withholding is typical unless you opt out or request a higher percentage.
State withholding varies by state. Some states mandate withholding, others make it voluntary, and several states have no income tax on retirement distributions at all. Your election affects your take-home amount and your tax bill when you file your return.
Form 1099-R Reporting
By January 31 following the year of your withdrawal, Principal Financial will issue Form 1099-R reporting the distribution to you and the IRS. This form includes:
- Total distribution amount
- Taxable amount
- Distribution code indicating the type of distribution
- Federal and state withholding amounts
- Your age at distribution
Distribution codes signal to the IRS whether penalties should apply. Code 1 indicates an early distribution potentially subject to the 10% penalty, while code 7 shows a normal distribution with no penalty due. Ensuring accurate coding prevents IRS inquiries and penalties.
Coordinating Withdrawals with Overall Financial Strategy
A principal financial 401k withdrawal should never occur in isolation from your comprehensive financial plan. Integration with other income sources, tax strategies, and long-term goals maximizes the value of your retirement assets.
Multi-Account Withdrawal Sequencing
Most retirees hold assets across multiple account types: taxable brokerage accounts, traditional IRAs, Roth IRAs, 401(k) plans, and perhaps Health Savings Accounts. The order in which you draw from these accounts significantly impacts lifetime tax liability and asset longevity.
A common withdrawal sequence strategy:
- RMDs first (mandatory by law once they begin)
- Taxable accounts (often lower capital gains rates than ordinary income)
- Tax-deferred accounts (traditional 401(k), traditional IRA)
- Tax-free accounts (Roth 401(k), Roth IRA, HSA for medical)
However, individual circumstances may warrant different approaches. High-income years might favor Roth withdrawals to avoid bracket creep. Low-income years present Roth conversion opportunities. Market downturns might suggest selling taxable accounts to harvest losses.
Estate Planning Considerations
Your withdrawal strategy impacts what you leave to heirs. Traditional 401(k) and IRA balances represent "tax bombs" for beneficiaries who inherit them, as distributions become taxable income to the recipients. The SECURE Act's elimination of the "stretch IRA" for most non-spouse beneficiaries means inherited retirement accounts must typically be emptied within 10 years.
Strategic lifetime withdrawals reduce the tax burden on your estate and beneficiaries. Converting traditional balances to Roth accounts during your lifetime (paying taxes at your potentially lower rate) can provide tax-free inheritance for your heirs. These strategies require coordination with estate planning advantages to align retirement distributions with legacy goals.
Healthcare Cost Planning
Medicare premium calculations and Affordable Care Act subsidy eligibility both depend on MAGI, which includes traditional 401(k) withdrawals. A large principal financial 401k withdrawal in a single year could:
- Push you into higher Medicare Part B and D premium brackets (affecting the following year's premiums)
- Eliminate or reduce ACA premium subsidies if you retire before Medicare eligibility
- Trigger the 3.8% Net Investment Income Tax on investment income if MAGI exceeds thresholds
Modeling these impacts before executing withdrawals helps optimize after-tax, after-healthcare-cost cash flow. Spreading distributions across multiple years or coordinating with Roth conversions in strategic years can mitigate these costs.
Common Mistakes to Avoid
Even well-intentioned retirement savers make costly errors when executing a principal financial 401k withdrawal. Awareness of these common pitfalls helps you avoid them:
Taking unnecessary hardship withdrawals: The permanent reduction in retirement savings and immediate tax hit often outweighs short-term benefits. Explore loans, home equity lines of credit, or other financing before tapping retirement funds.
Missing the 60-day rollover deadline: If you receive a distribution with the intent to roll it to an IRA, you must complete the rollover within 60 days or face taxation and potential penalties. Direct rollovers avoid this risk entirely.
Failing to update beneficiary designations: Outdated beneficiary designations can send your retirement assets to unintended recipients. Review and update these annually or after major life events.
Withdrawing in high-income years: Taking distributions while still working or during a year with unusual income (business sale, real estate transaction) maximizes your tax burden unnecessarily.
Neglecting state tax differences: If you're planning to relocate in retirement, consider timing large distributions after establishing residency in a lower-tax state.
Overlooking penalty exceptions: Several exceptions to the 10% early withdrawal penalty exist (disability, certain medical expenses, substantially equal periodic payments), but you must properly document and structure distributions to qualify.
Working with professionals who understand the nuances of retirement planning helps you navigate these complexities and avoid expensive mistakes.
The Role of Professional Guidance
The complexity of retirement distribution planning has increased substantially with the SECURE Act, SECURE 2.0, changing RMD ages, and the interaction between retirement withdrawals and other income sources. Professional guidance provides value in several key areas:
Comprehensive Tax Planning
Coordinating retirement distributions with other income sources, deductions, credits, and multi-year tax strategies requires sophisticated modeling that most individuals lack the tools or expertise to perform independently. Professionals can project tax liabilities under various distribution scenarios, identifying the most tax-efficient approach.
Regulatory Compliance
Staying current with changing regulations, understanding plan-specific rules, and ensuring proper documentation prevents costly penalties and mistakes. Fiduciary advisors maintain this expertise as part of their professional responsibility.
Behavioral Coaching
Research consistently shows that individual investors make emotionally-driven decisions that undermine long-term results. Professional advisors provide objective perspective during market volatility, helping you maintain disciplined withdrawal strategies regardless of market conditions.
Integration Across Planning Domains
Retirement distribution planning intersects with investment management, tax planning, estate planning, insurance analysis, and cash flow management. Comprehensive advice ensures these elements work together harmoniously rather than at cross-purposes.
Navigating a principal financial 401k withdrawal successfully requires understanding your plan's specific provisions, federal tax regulations, and how distributions integrate with your comprehensive financial strategy. The decisions you make about accessing retirement funds impact your tax liability, retirement security, and legacy for decades to come. Brookwood Investment Group LLC provides fiduciary guidance that prioritizes your best interests, offering personalized strategies for retirement distributions, tax optimization, and comprehensive wealth management tailored to your unique circumstances and goals.
