Managing a workplace retirement account requires understanding your plan's specific features, investment options, and distribution rules. For participants in a john hancock pension 401k plan, navigating the available choices becomes easier when you understand how these accounts work, what options you have when changing jobs, and how to align your retirement savings with your broader financial goals. Whether you're actively contributing, nearing retirement, or considering a rollover, knowing the mechanics of your plan can help you make informed decisions that support your long-term financial security.
Understanding John Hancock 401(k) Plan Structures
John Hancock serves as a recordkeeper and administrator for thousands of employer-sponsored retirement plans across the United States. When your employer selects John Hancock to manage the company's 401(k) plan, you gain access to a platform that handles contributions, investment selections, loan provisions, and distribution processing.
The structure of a john hancock pension 401k typically includes several key components. Your employer establishes the plan document that governs contribution limits, matching formulas, vesting schedules, and withdrawal provisions. John Hancock then provides the administrative infrastructure, including participant accounts, investment lineup management, and compliance reporting.
Plan Features and Participant Options
Most John Hancock-administered plans offer the following features:
- Pre-tax and Roth contribution options for different tax planning strategies
- Employer matching contributions based on your company's specific formula
- Automatic enrollment and escalation to encourage consistent saving
- Loan provisions allowing borrowing against vested balances
- Target-date funds and diversified investment menus
- Online account management through the participant portal
The investment menu within your plan reflects selections made by your employer's retirement committee. These typically include mutual funds, index funds, stable value options, and company stock in some cases. Understanding your specific menu helps you build an appropriate asset allocation based on your timeline and risk tolerance.
| Plan Element | Employer Controls | John Hancock Provides |
|---|---|---|
| Contribution limits | Match percentage, eligibility | System enforcement of IRS caps |
| Investment options | Menu selection, oversight | Fund administration, reporting |
| Vesting schedule | Years of service requirements | Tracking, calculation |
| Loan provisions | Availability, terms | Processing, repayment tracking |
Working with fiduciary advisors can help you evaluate whether your current investment selections align with your retirement timeline and risk capacity.
Distribution Rules and Withdrawal Options
Understanding when and how you can access funds in your john hancock pension 401k matters significantly for planning purposes. The IRS 401(k) Resource Guide for Plan Participants outlines the federal requirements that govern all qualified retirement plans, including those administered by John Hancock.
Qualifying Distribution Events
You can typically take distributions from your 401(k) when you experience a qualifying event:
- Separation from service (leaving your employer)
- Reaching age 59½ while still employed (if plan allows)
- Disability as defined by the plan
- Financial hardship meeting IRS criteria
- Plan termination by the employer
- Required minimum distributions beginning at age 73
Each distribution type carries specific tax implications and potential penalties. Taking withdrawals before age 59½ generally triggers a 10% early withdrawal penalty in addition to ordinary income tax, unless you qualify for an exception.
In-Service Withdrawals and Loans
Some john hancock pension 401k plans permit in-service withdrawals after reaching age 59½, allowing you to access funds while still working. This feature varies by plan, so reviewing your summary plan description clarifies what's available.
Plan loans offer another access option, typically allowing you to borrow up to 50% of your vested balance or $50,000, whichever is less. While loans avoid taxes and penalties if repaid according to schedule, they reduce your invested balance and can create complications if you leave your employer before repayment.
If you're considering a withdrawal for specific purposes such as purchasing your first home, understanding the rules around first-time home buyer 401k withdrawal provisions becomes essential.
Rollover Strategies When Changing Employers
Career transitions create important decision points for your john hancock pension 401k. When you leave an employer, you typically have four primary options for your accumulated retirement savings.
Your Four Main Options
Leave money in the existing plan: If your balance exceeds $7,000, most plans allow you to maintain your account even after separation. This keeps your investments growing tax-deferred and maintains access to your current fund lineup.
Roll over to your new employer's plan: If your new company offers a 401(k) and accepts incoming rollovers, consolidating accounts can simplify management and reduce administrative complexity.
Roll over to an Individual Retirement Account (IRA): This option typically provides the broadest investment selection and greatest control over your retirement assets. The Treasury/IRS guidance on rollovers between retirement plans clarifies the standardized processes that make transfers more straightforward.
Cash out the account: Taking a taxable distribution triggers immediate taxes and potential penalties, making this the least advantageous option in most circumstances.
The AARP guide on what happens to your 401(k) when changing jobs provides consumer-focused perspectives on weighing these choices based on your situation.
| Rollover Option | Advantages | Considerations |
|---|---|---|
| Leave in plan | Familiar investments, no action needed | Limited to existing menu, potential fees |
| New employer plan | Consolidation, possible loan access | May have waiting period, limited options |
| IRA rollover | Maximum flexibility, broader choices | Need to select custodian, self-directed |
| Cash distribution | Immediate access | Taxes, penalties, lost growth potential |
For those with pension benefits alongside their 401(k), exploring pension lump sum rollover to IRA strategies can help coordinate multiple retirement income sources.
Investment Management Within Your Plan
The investment selections you make within your john hancock pension 401k significantly impact your retirement readiness. Most plans offer tiered investment menus designed to accommodate participants with varying levels of investment knowledge and engagement.
Common Investment Categories
Target-date funds automatically adjust asset allocation as you approach retirement, becoming more conservative over time. These "set it and forget it" options work well for participants who prefer simplified management.
Index funds track specific market benchmarks with low expense ratios, providing cost-effective exposure to broad market segments like large-cap stocks, international equities, or bonds.
Actively managed funds employ professional managers who select securities aiming to outperform benchmark indices, though they typically carry higher expense ratios.
Stable value or money market options provide principal protection for conservative investors or those nearing retirement who prioritize capital preservation.
Building an Appropriate Allocation
Your ideal investment mix depends on several personal factors:
- Time until retirement (your investment horizon)
- Risk tolerance and capacity for volatility
- Other retirement savings and income sources
- Current financial obligations and cash flow needs
- Tax diversification across account types
Younger participants with 30+ years until retirement typically benefit from higher equity allocations that capture long-term growth potential. Those within 10 years of retirement often shift toward more balanced approaches that reduce volatility while maintaining growth exposure.
Regular rebalancing ensures your allocation doesn't drift significantly from your target as different asset classes perform differently over time. Many john hancock pension 401k plans offer automatic rebalancing features that maintain your desired mix without manual intervention.
Working with retirement planning advisors helps ensure your 401(k) investments coordinate with your broader financial strategy, including taxable accounts, IRAs, and other retirement vehicles.
Maximizing Employer Matching Contributions
One of the most valuable features of any 401(k) plan, including those administered by John Hancock, is the employer matching contribution. This represents free money that immediately boosts your retirement savings, yet many participants fail to capture the full match available to them.
Understanding Match Formulas
Employer matches typically follow one of several common formulas:
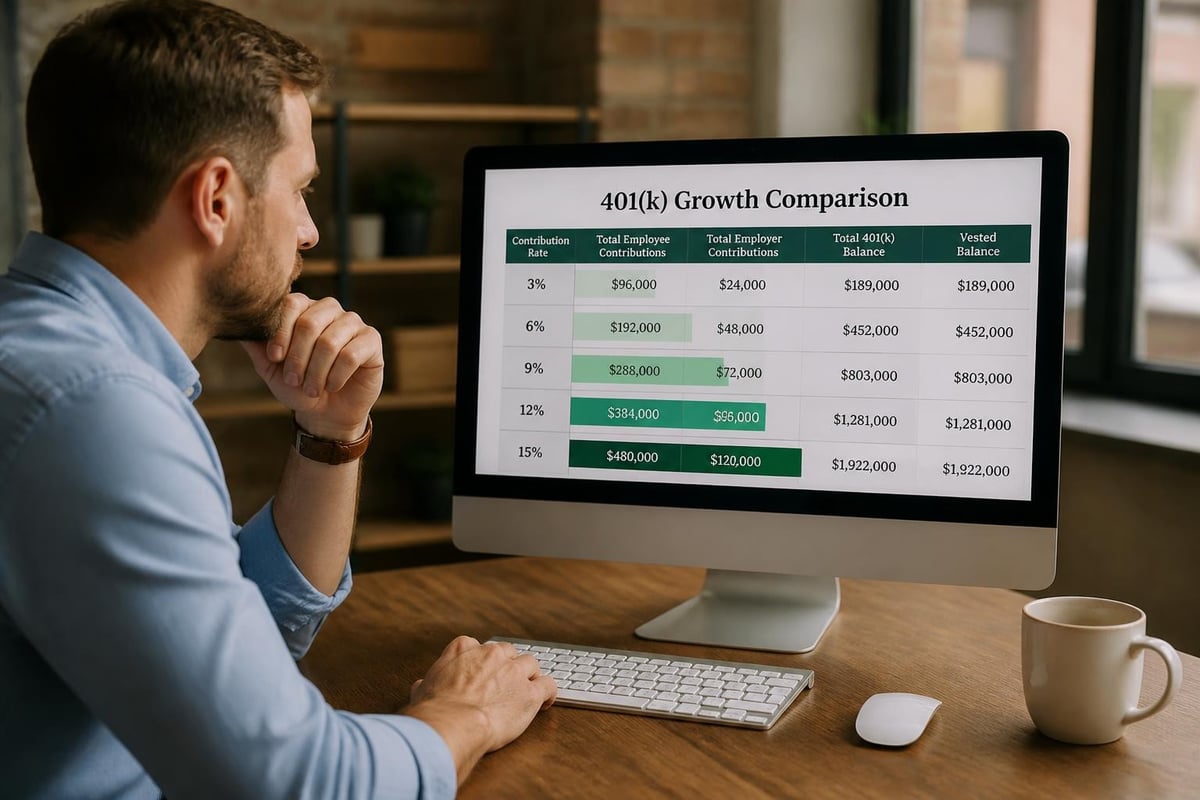
- Dollar-for-dollar match up to a specific percentage (e.g., 100% match on first 3% of salary)
- Partial match at a reduced rate (e.g., 50% match on first 6% of salary)
- Tiered match with different rates at different contribution levels
- Non-elective contributions made regardless of employee contributions
To maximize your benefit, contribute at least enough to capture the full employer match. If your company matches 100% on the first 4% of your salary, contributing only 2% means you're leaving 2% of your compensation on the table.
Vesting Schedules and Timing
While your own contributions are always 100% vested (they belong to you immediately), employer contributions often follow a vesting schedule. Understanding your john hancock pension 401k vesting provisions matters particularly when considering job changes.
Common vesting schedules include:
- Immediate vesting (you own employer contributions right away)
- Cliff vesting (0% until a specific anniversary, then 100%)
- Graded vesting (percentage increases each year until fully vested)
If you're considering leaving your employer before becoming fully vested, calculate the value of unvested contributions you'd forfeit. Sometimes staying a few additional months can significantly increase your retirement nest egg.
Tax Planning Considerations for Account Holders
Your john hancock pension 401k exists within a broader tax planning framework that affects both current-year tax liability and retirement income taxation. Understanding these dynamics helps you make strategic decisions about contribution types, withdrawal timing, and account coordination.
Pre-Tax vs. Roth Contributions
Traditional pre-tax 401(k) contributions reduce your current taxable income, providing immediate tax savings. You pay ordinary income tax on withdrawals in retirement. Roth 401(k) contributions use after-tax dollars now, but qualified distributions in retirement are completely tax-free.
The decision between these contribution types depends on your current tax bracket versus your expected retirement tax bracket. Younger workers in lower brackets often benefit from Roth contributions, while high earners approaching peak earning years may prefer pre-tax contributions.
Many participants benefit from splitting contributions between both types, creating tax diversification that provides flexibility in managing retirement income tax liability.
Required Minimum Distributions
Once you reach age 73, federal law requires you to begin taking required minimum distributions (RMDs) from your john hancock pension 401k, unless you're still working for the plan sponsor and don't own 5% or more of the company. RMDs are calculated based on your account balance and IRS life expectancy tables.
Failing to take required distributions triggers a substantial penalty: 25% of the amount you should have withdrawn (reduced to 10% if corrected quickly). Planning for RMDs helps ensure you meet these obligations while managing your overall tax situation effectively.
Coordination with Other Accounts
Strategic tax planning considers your 401(k) alongside other retirement and investment accounts:
- Traditional and Roth IRAs for additional tax-deferred or tax-free growth
- Taxable brokerage accounts offering flexibility without withdrawal restrictions
- Health Savings Accounts providing triple tax advantages
- Pension income if available from your employer or previous employers
Consulting with financial planning professionals who understand the interaction between these account types can help optimize your lifetime tax efficiency and withdrawal sequencing strategies.
Beneficiary Designations and Estate Planning
Your john hancock pension 401k beneficiary designation determines who receives your account assets if you pass away before fully depleting the balance. This designation supersedes your will, making it a critical estate planning component that deserves regular review and updating.
Primary and Contingent Beneficiaries
You can name one or more primary beneficiaries to receive your 401(k) assets, specifying the percentage each should receive. Contingent (or secondary) beneficiaries inherit only if all primary beneficiaries predecease you.
Federal law requires spousal consent if you're married and wish to name someone other than your spouse as primary beneficiary. This protection ensures your spouse isn't inadvertently disinherited from this significant asset.
Review and update beneficiary designations when you experience major life events:
- Marriage or divorce
- Birth or adoption of children
- Death of a named beneficiary
- Significant relationship changes
- Estate plan updates
Coordination between your 401(k) beneficiary designations and your broader estate planning strategy ensures your assets transfer according to your wishes while minimizing tax complications for your heirs.
Inherited 401(k) Rules for Beneficiaries
Beneficiaries who inherit your john hancock pension 401k face specific distribution rules that vary based on their relationship to you. Spousal beneficiaries enjoy the most flexible options, including the ability to roll inherited funds into their own IRA or treat the account as their own.
Non-spousal beneficiaries typically must deplete inherited accounts within 10 years, though exceptions exist for certain eligible designated beneficiaries. These rules significantly impact the tax efficiency of wealth transfer, making strategic beneficiary selection important for account holders with substantial balances.
Plan Fees and Cost Considerations
Investment expenses directly impact your long-term retirement accumulation. Within your john hancock pension 401k, you encounter several types of fees that reduce your net returns over time.
Fee Categories Explained
Investment expense ratios: Each fund in your plan menu charges an annual expense ratio, typically ranging from 0.05% for index funds to 1.5% or more for actively managed options. These fees are deducted automatically from fund returns.
Administrative fees: Your employer may pay these costs, or they may be charged to participant accounts as a flat dollar amount or percentage of assets.
Individual service fees: Charges for specific services like plan loans, hardship withdrawals, or expedited distributions vary by plan and service type.
| Fee Type | Typical Range | Impact on $100,000 Account (Annual) |
|---|---|---|
| Low-cost index fund | 0.05% – 0.20% | $50 – $200 |
| Actively managed fund | 0.50% – 1.50% | $500 – $1,500 |
| Administrative fees | 0.25% – 0.75% | $250 – $750 |
| Combined total | 0.30% – 2.25% | $300 – $2,250 |
Even seemingly small fee differences compound dramatically over decades. A 1% annual fee difference on a $100,000 balance growing at 7% annually costs over $60,000 in lost returns over 25 years.
Evaluating Investment Options
When selecting funds within your john hancock pension 401k, compare expense ratios among similar investment categories. If your plan offers both an actively managed large-cap fund charging 1.2% and a large-cap index fund charging 0.15%, the index option provides a 1.05% annual advantage that compounds throughout your career.
Review your quarterly account statements to identify all fees being charged. Understanding your total cost picture helps you make informed decisions about investment selections and whether consolidating accounts through a rollover might reduce ongoing expenses.
Coordinating Your 401(k) with Comprehensive Retirement Planning
Your john hancock pension 401k represents one component of a complete retirement strategy. Effective planning integrates this account with your other assets, income sources, and financial goals to create a cohesive approach to retirement readiness.
Income Source Diversification
Most successful retirement plans draw from multiple income sources:
- Social Security benefits based on your earnings history
- Pension income if available from your employer
- 401(k) and IRA distributions from tax-deferred accounts
- Taxable investment account withdrawals
- Roth account distributions for tax-free income
- Part-time work or business income during early retirement
Diversifying across these sources provides flexibility in managing annual tax liability and adapting to changing circumstances during retirement.
Withdrawal Sequencing Strategies
The order in which you tap different accounts significantly affects how long your money lasts and your lifetime tax bill. Common strategies include:
Tax-deferred first: Depleting 401(k) and traditional IRA assets early can reduce RMD amounts later, though it may increase current taxes.
Taxable accounts first: Using brokerage accounts initially preserves tax-deferred growth and delays RMDs, potentially keeping you in lower tax brackets longer.
Proportional withdrawals: Taking from multiple account types simultaneously creates consistent tax liability and maintains diversification.
The optimal approach depends on your specific tax situation, account balances, and income needs. Investment management services can help model different withdrawal scenarios to identify the most efficient strategy for your circumstances.
Retirement Readiness Assessment
Evaluating whether you're on track for retirement involves more than simply accumulating a target dollar amount. Consider these factors:
- Projected retirement expenses and lifestyle goals
- Healthcare costs and insurance coverage gaps
- Longevity assumptions and family health history
- Inflation's impact on purchasing power over 30+ years
- Legacy goals and wealth transfer objectives
Regular reviews ensure your savings rate, investment allocation, and projected accumulation align with your retirement timeline and income needs. Adjustments made early in your career have dramatically more impact than changes attempted in your final working years.
Successfully managing your John Hancock 401(k) requires understanding plan-specific features, tax implications, investment options, and how this account fits within your comprehensive financial strategy. Whether you're evaluating rollover decisions, optimizing contribution strategies, or planning withdrawal sequences, these choices work together to shape your retirement security. Brookwood Investment Group provides personalized, fiduciary guidance to help you coordinate your workplace retirement accounts with your broader financial goals, offering virtual-first advisory services tailored to your unique situation and retirement timeline.
