Building a reliable stream of retirement passive income has become a central concern for individuals approaching or navigating their post-career years. Unlike active employment income, passive sources provide regular cash flow without ongoing labor, allowing retirees to maintain their desired lifestyle while preserving capital. Understanding the various mechanisms available and how they fit within a comprehensive financial strategy requires careful analysis of risk tolerance, time horizon, tax implications, and individual circumstances.
Understanding Retirement Passive Income Fundamentals
Retirement passive income represents cash flow generated from investments, assets, or arrangements that require minimal ongoing effort to maintain. This differs fundamentally from pension payments or Social Security, which are classified as retirement benefits rather than passive income in the traditional sense.
The distinction matters because passive income sources typically require upfront capital allocation decisions and ongoing management through a financial professional. These sources include dividend-paying equities, fixed-income securities, real estate investment trusts, annuities, and systematic withdrawal strategies from diversified portfolios.
Key characteristics of effective retirement passive income include:
- Predictability and consistency of payment schedules
- Tax efficiency relative to other income sources
- Inflation protection mechanisms or adjustment features
- Liquidity options for unexpected expenses
- Sustainability over a 25-35 year retirement horizon
Many retirees discover that combining multiple income sources creates resilience against market volatility, interest rate changes, and unexpected expenses. A fiduciary financial advisor evaluates these components within the context of your complete financial picture.
Portfolio Income: Dividends and Interest
Dividend-paying stocks and interest-bearing bonds form the cornerstone of many retirement passive income strategies. These asset classes have historically provided regular distributions while potentially maintaining or growing principal value over time.
Dividend-Focused Equity Strategies
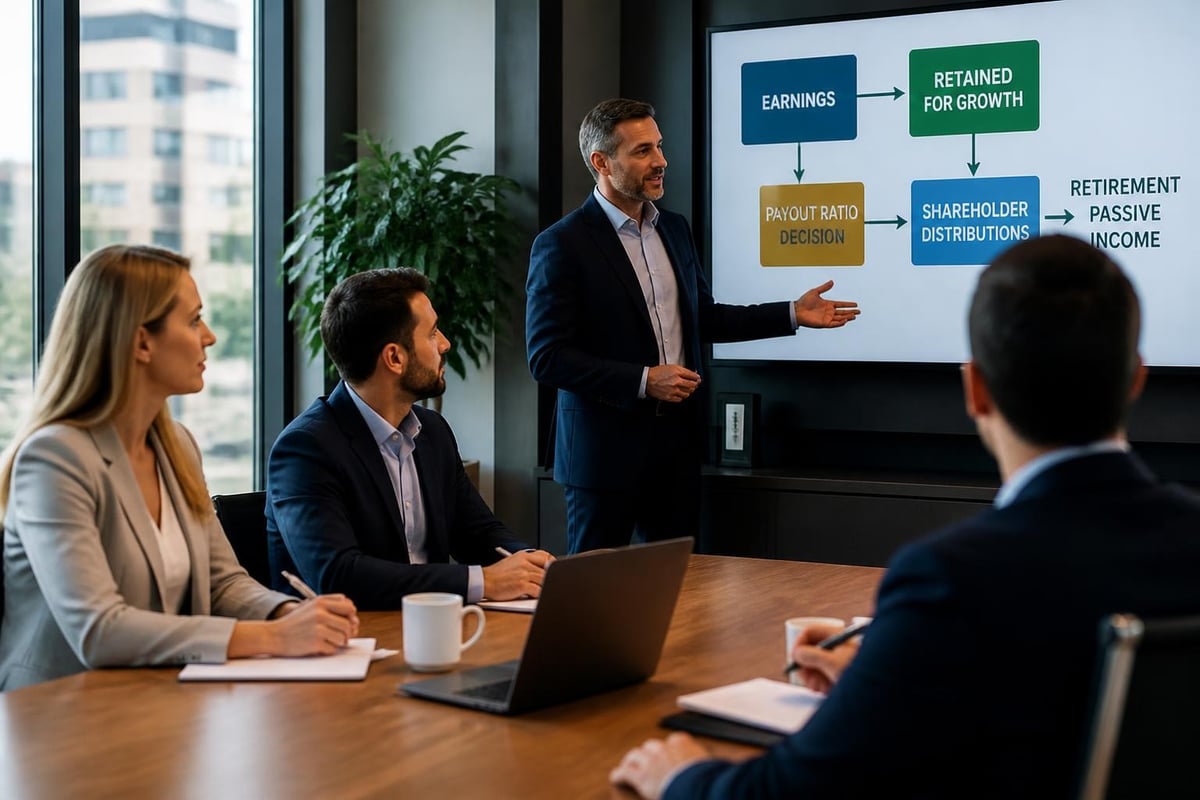
Dividend stocks from established companies offer quarterly or monthly payments alongside potential capital appreciation. This dual benefit makes them attractive for retirement portfolios seeking both income and growth.
Quality dividend payers typically demonstrate:
- Consistent earnings growth supporting regular distributions
- Manageable payout ratios below 70-80% of earnings
- Dividend growth histories spanning decades
- Strong balance sheets with reasonable debt levels
However, dividends are not guaranteed. Companies may reduce or eliminate payments during economic downturns, and dividend income carries tax implications that vary based on whether distributions qualify for preferential rates.
Fixed-Income Securities and Bond Ladders
Bonds provide contractual interest payments on predetermined schedules, offering greater predictability than equity dividends. Treasury bonds, municipal bonds, corporate bonds, and agency securities each serve distinct roles in retirement income planning.
Bond ladder strategies distribute maturities across multiple years, providing:
- Regular principal returns for reinvestment or spending
- Reduced interest rate sensitivity compared to single-maturity holdings
- Natural rebalancing opportunities as bonds mature
- Predictable cash flow matching retirement expenses
| Bond Type | Tax Treatment | Credit Risk | Typical Yield (2026) |
|---|---|---|---|
| U.S. Treasury | Federally taxable, state-exempt | Minimal | 3.5-4.5% |
| Municipal | Often tax-exempt | Varies by issuer | 2.5-4.0% |
| Investment-Grade Corporate | Fully taxable | Low to moderate | 4.5-5.5% |
| High-Yield Corporate | Fully taxable | Moderate to high | 6.5-8.5% |
Interest rate fluctuations affect bond values inversely, though holders maintaining positions to maturity receive full principal regardless of interim price movements.
Systematic Withdrawal Strategies
Rather than relying solely on investment distributions, many retirees implement systematic withdrawal programs that sell portfolio shares on regular schedules to generate retirement passive income. This approach provides flexibility in asset allocation without constraining investments to only income-producing securities.
The traditional 4% rule suggested withdrawing that percentage of initial portfolio value annually, adjusting for inflation in subsequent years. Recent research, including Morningstar’s analysis of withdrawal strategies, suggests that this guideline requires adjustment based on market valuations, interest rates, and portfolio composition at retirement commencement.
Contemporary withdrawal approaches consider:
- Current market conditions and sequence-of-returns risk
- Portfolio composition between stocks, bonds, and alternatives
- Tax-bracket management through strategic account withdrawals
- Required Minimum Distribution coordination after age 73
- Flexibility to reduce spending during market downturns
Dynamic withdrawal strategies adjust spending based on portfolio performance, potentially sacrificing spending predictability for improved sustainability. Fixed-percentage approaches withdraw a constant percentage of current portfolio value, automatically adjusting spending to market conditions.
When implementing a pension lump sum rollover to IRA, understanding systematic withdrawal mechanics becomes particularly important, as the lump sum provides the capital base supporting future income needs.
Annuities as Retirement Passive Income Tools
Annuities represent contractual arrangements with insurance companies that convert lump-sum capital into guaranteed income streams. These instruments address longevity risk by providing payments continuing for life, regardless of how long you live.
Types of Income Annuities
Immediate annuities begin payments within one year of purchase, converting capital into immediate retirement passive income. These suit retirees seeking to establish baseline income covering essential expenses.
Deferred income annuities begin payments at a future date, potentially decades after purchase. This delay allows the insurance company to credit higher payment rates, making them efficient for future income needs established today.
Variable annuities with living benefits invest in market-based subaccounts while providing guaranteed minimum income regardless of account performance. These complex products combine investment exposure with income protection, though fees typically exceed those of simpler alternatives.
Understanding annuity features and considerations helps retirees evaluate whether guaranteed income justifies the illiquidity and fees these products entail. The SEC’s investor guidance on annuities provides additional consumer protection perspectives.
Annuity Considerations
| Feature | Benefit | Tradeoff |
|---|---|---|
| Lifetime income guarantee | Eliminates longevity risk | Illiquid capital commitment |
| Fixed payment schedules | Predictable budgeting | Limited inflation protection |
| Death benefit options | Potential legacy for heirs | Reduced income payments |
| Tax deferral during accumulation | Compounding growth | Ordinary income tax on distributions |
Research examining behavioral factors in annuity adoption reveals that many retirees underutilize annuities despite their efficiency in addressing longevity risk, often due to liquidity concerns or preference for maintaining investment control.
Real Estate Investment Approaches
Real estate provides retirement passive income through rental properties, real estate investment trusts, or real estate crowdfunding platforms. Each approach carries distinct management requirements, liquidity characteristics, and risk profiles.
Direct Rental Property Ownership
Physical rental properties generate monthly rent payments while potentially appreciating in value. However, "passive" characterization depends on management arrangements, as landlord responsibilities can become quite active without professional property management.
Successful rental property strategies require:
- Sufficient cash reserves for maintenance, vacancies, and capital improvements
- Property management infrastructure or professional management contracts
- Diversification across multiple properties reducing single-tenant dependency
- Understanding of landlord-tenant regulations in relevant jurisdictions
- Exit strategy planning for eventual liquidation needs
Rental income taxation differs from portfolio income, with deductions available for mortgage interest, property taxes, depreciation, and operating expenses. These tax benefits can enhance after-tax returns relative to equivalent portfolio income.
Real Estate Investment Trusts (REITs)
REITs provide real estate exposure through publicly traded securities, distributing at least 90% of taxable income to shareholders. This structure creates consistent dividend payments while maintaining stock market liquidity.
REIT categories include:
- Equity REITs owning and operating properties
- Mortgage REITs holding real estate debt instruments
- Hybrid REITs combining property ownership and mortgage holdings
- Sector-specific REITs focusing on retail, office, residential, healthcare, or industrial properties
REIT dividends typically receive less favorable tax treatment than qualified corporate dividends, with most distributions taxed as ordinary income. This makes them potentially better suited for tax-advantaged retirement accounts.
Tax-Efficient Income Positioning
Strategic account location of income-producing assets significantly impacts after-tax retirement passive income. Tax-bracket management through coordinated withdrawals from taxable, tax-deferred, and tax-free accounts enhances spending power.
Account Type Considerations
Taxable brokerage accounts receive step-up in cost basis at death, making them suitable for growth-oriented holdings intended as legacy assets. Qualified dividends and long-term capital gains receive preferential rates, while interest income faces ordinary income taxation.
Traditional IRA and 401(k) accounts defer taxation until withdrawal, when distributions are taxed as ordinary income. The IRS Required Minimum Distribution rules mandate withdrawals beginning at age 73, potentially creating income whether needed or not.
Roth IRA accounts provide tax-free qualified distributions, making them valuable for managing taxable income in retirement. Strategic Roth conversions during lower-income years can reduce future RMDs while creating tax-free income sources.
A three-bucket withdrawal strategy draws from different account types based on tax efficiency:
- Taxable accounts for initial retirement years, utilizing low capital gains rates
- Tax-deferred accounts for middle retirement years, managing ordinary income
- Roth accounts preserved for later years, high-expense years, or legacy purposes
This sequencing potentially reduces lifetime tax burden while maximizing retirement passive income sustainability. Comprehensive retirement planning services coordinate these strategies within personalized financial plans.
Coordinating Multiple Income Sources
Effective retirement passive income strategies rarely rely on single sources. Instead, they combine complementary approaches creating resilience against various risks.
Building a Diversified Income Portfolio
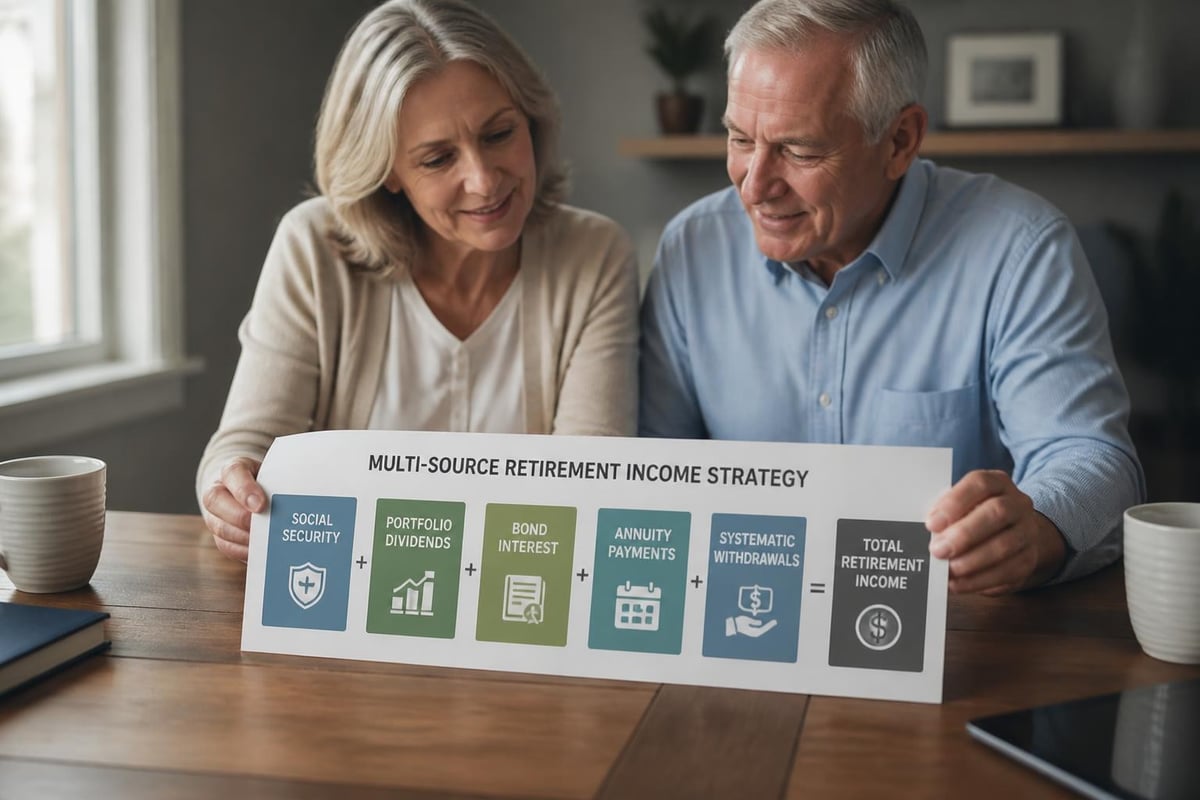
Consider a retiree requiring $80,000 annual income to maintain their lifestyle. Rather than depending entirely on portfolio withdrawals, a diversified approach might include:
- $24,000 from Social Security benefits
- $18,000 from dividend-paying stock portfolio
- $12,000 from bond interest and Treasury securities
- $15,000 from immediate annuity payments
- $11,000 from systematic portfolio withdrawals
This structure provides $44,000 from relatively stable sources (Social Security, bonds, annuity) and $36,000 from market-dependent sources (dividends, withdrawals), balancing security with growth potential.
Inflation Protection Mechanisms
Long retirement horizons demand consideration of purchasing power preservation. Federal Reserve household economic data reveals that many retirees underestimate inflation's cumulative impact over 25-30 year retirements.
Inflation protection strategies include:
- Treasury Inflation-Protected Securities (TIPS) adjusting principal with CPI
- Dividend growth stocks with histories of above-inflation distribution increases
- Real estate holdings benefiting from rent escalations
- Annuities with cost-of-living adjustment riders (though with reduced initial payments)
- Maintaining equity exposure providing long-term growth potential
The appropriate inflation protection mix depends on spending flexibility, legacy intentions, and risk capacity. Those with significant discretionary spending can potentially tolerate more inflation risk than retirees with fixed essential expenses consuming most income.
Professional Planning Considerations
Developing sustainable retirement passive income requires integrating investment management, tax planning, estate considerations, and risk management. The complexity of coordinating multiple strategies while adapting to changing circumstances often warrants professional guidance.
Questions to ask when evaluating retirement income planning advisors help identify professionals with relevant expertise and appropriate credentials. Fiduciary advisors commit to acting in client best interests, avoiding conflicts inherent in commission-based product sales.
Ongoing Plan Maintenance
Retirement passive income strategies require regular review and adjustment responding to:
- Market condition changes affecting portfolio values and yields
- Tax law modifications altering optimal withdrawal sequences
- Health status updates influencing longevity assumptions and care costs
- Spending pattern evolution as retirement progresses through distinct phases
- Estate planning refinements reflecting family circumstances
Annual reviews with a financial professional ensure strategies remain aligned with current circumstances while capitalizing on new planning opportunities. Virtual-first advisory models provide convenient access to specialized expertise regardless of geographic location.
Risk Management in Retirement Income
Several risks threaten retirement passive income sustainability beyond simple investment volatility. Comprehensive planning addresses these interconnected challenges.
Longevity risk represents the possibility of outliving financial resources. Increasing life expectancies mean planning for potentially 30-35 year retirements, with significant probabilities of one spouse surviving beyond age 95 in married couples.
Sequence-of-returns risk describes how the timing of market declines impacts portfolio sustainability. Poor returns in early retirement years, when portfolios are largest and withdrawals represent the greatest percentage of holdings, can permanently impair future income capacity even if markets eventually recover.
Healthcare cost risk encompasses both routine medical expenses and potential long-term care needs. Medicare covers many costs but leaves significant gaps, particularly for extended care facility stays or home health services.
Inflation risk erodes purchasing power over time, with even modest 2-3% annual inflation reducing real income by 30-40% over typical retirement periods. Essential expenses like healthcare often inflate faster than general price indices.
Addressing these risks requires combining guaranteed income sources, maintaining appropriate equity exposure for growth, establishing healthcare contingency reserves, and building flexibility into spending plans.
Generating sustainable retirement passive income requires thoughtful integration of multiple strategies tailored to individual circumstances, risk tolerance, and financial goals. By combining portfolio income, systematic withdrawals, annuity considerations, and tax-efficient positioning, retirees create resilient income structures supporting desired lifestyles throughout retirement. Brookwood Investment Group specializes in personalized retirement income planning, helping clients develop comprehensive strategies coordinating investment management, tax efficiency, and estate considerations within fiduciary relationships designed around their unique situations.
